
Top 100 AI StocksA 2026 guide to the companies building, powering and selling artificial intelligence
This guide profiles 100 publicly traded companies with meaningful exposure to AI, from the chip designers at the center of the build-out to the cloud platforms, data center developers, software vendors, power producers and contractors around them. Each entry covers what the company does in AI, its latest reported figures and the issues to check before treating it as an AI investment.
- NVIDIA Data Center revenue, quarter to July 26
- ~$89bn, up 117%
- Five largest hyperscalers, 2026 capex (BofA estimate)
- ~$700bn
- CoreWeave revenue backlog, September 30
- ~$132.5bn
- VanEck Semiconductor ETF below peak, November 3
- 24.3%
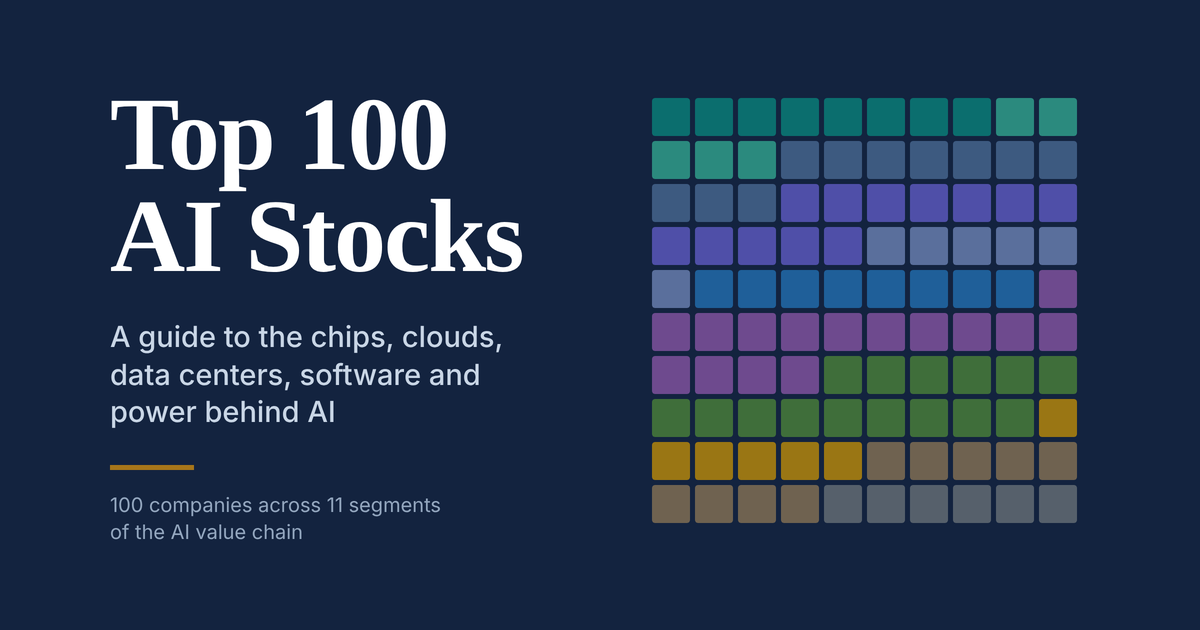
The list follows the AI value chain, from power generation at the bottom to software at the top. Band length reflects the number of companies in each layer; select a layer to jump to its chapter.
In this guide
- Where the AI trade stands
- The 100 at a glancesortable list
- Compute and accelerator chips1–8
- Memory and storage9–13
- Foundry, equipment and chip design14–23
- Networking, optics and connectivity24–35
- Servers and systems36–41
- Hyperscalers and platforms42–49
- Neoclouds and data center operators50–64
- Enterprise software and AI applications65–79
- Power generation80–85
- Electrical, cooling and grid equipment86–94
- Construction and engineering95–100
- Analyst and strategist picks
- The case for and against
- Seven checks before buying
- AI ETFs and concentration
- Glossary
- Method and sources
Where the AI trade stands in November 2026
AI demand is showing up clearly in reported results. The questions investors are now asking are about cash: how much of the spending is being financed with debt, how long the equipment will stay useful, and which companies will earn an adequate return on what they are building. Those questions drove a sharp selloff in late October and early November, followed by a relief rally on November 11.
A relief rally after CoreWeave reported
CoreWeave reported third-quarter revenue of $3.66bn on November 10, raised its full-year outlook and said it expected ~$9bn of customer prepayments and deposits over the following three months. The next morning Benzinga counted 17 AI stocks up more than 10% in late-morning trading, spanning neoclouds, memory, optics, servers and power. A separate Benzinga report tied gains in IREN, Galaxy Digital, SharonAI and Applied Digital to the same results.
Those moves trace back to one catalyst, so they are not 17 separate confirmations that each company’s business improved. The mood also did not last uniformly: on November 12 Nebius fell about 16% after saying 2026 revenue would land near the low end of its range.
Seventeen AI stocks rose more than 10% on November 11
Intraday change and share price at the time of Benzinga’s late-morning report
The selloff that came before it
Hyperscalers and chipmakers lost more than $800bn of market value in the week ended October 30, according to Benzinga. By November 2 the Technology Select Sector SPDR ETF (XLK) was 14.3% below its record, and by November 3 the VanEck Semiconductor ETF (SMH) was 24.3% below its peak. On November 10 selling spread to power, cooling, electrical, fiber and construction suppliers, even though many of them had reported strong demand.
Politics added to the pressure after the midterm elections. Investor Brad Gerstner warned that 10 to 15 gigawatts of expected 2027 data center capacity could be delayed by permitting changes. Bernstein estimated a much smaller effect of 2% to 4% on credible nationwide capacity, and favored operating assets with secured power. The two estimates use different denominators and time frames. On November 12 Benzinga reported that voters had rejected data center projects in 10 states; proposed restrictions are not the same as cancelled projects.
Valuations reset, on estimates that assume strong growth
Technology now trades at roughly the same forward earnings multiple as the broader index, and chip stocks trade at a discount to both. Those multiples depend on forecasts of very fast earnings growth. Cantor Fitzgerald and HSBC described the chip decline as a mid-cycle correction and favored NVIDIA, Broadcom, AMD, Micron, Sandisk, ASML, Applied Materials, Lam Research and KLA, while acknowledging that low multiples on cyclical profits can turn into value traps.
Spending keeps rising, and so does the borrowing
Alphabet guides to $195−205bn of capital spending in 2026, Microsoft to about $170bn, and Meta to $135−145bn. Amazon spent $210.7bn on property and equipment, net of proceeds, in the 12 months to September. A Bank of America estimate cited by Benzinga puts 2026 capex for the five largest hyperscalers near $700bn and 2027 above $1tn.
More of that spending is being financed with debt. The same report cited estimates that the five largest hyperscalers issued more than $180bn of US investment-grade bonds through midsummer 2026, compared with about $28bn a year on average from 2020 to 2024. Carlyle’s Jason Thomas estimated that AI infrastructure could require about $5tn of investment, with up to $1tn coming from private credit. An October Benzinga analysis collected forecasts that hyperscaler depreciation could reach $500bn to $1tn a year by the end of the decade, and that up to 40% of 2026 AI capital spending will not be in service until 2027 to 2029. These are third-party estimates and forecasts, not reported results.
What fund managers told Bank of America
In the September Global Fund Manager Survey of 190 managers overseeing about $512bn in assets, a majority named semiconductors the most crowded trade, and the share naming AI capex as the top systemic credit risk rose from August. A larger share also said they did not expect the big AI spenders to cut capital spending.
Fund managers see crowded chip positioning and rising credit risk
Share of respondents, BofA Global Fund Manager Survey
The 100 at a glance
Filter by segment or search by ticker, name or theme. Select a ticker to jump to its profile. Numbering follows the chapter order below and does not rank the companies against one another.
Showing 100 of 100 companies
| Segment | AI exposure | In this guide | |||
|---|---|---|---|---|---|
| 1 | NVDA | NVIDIA | Compute and accelerator chips | GPUs, networking and CUDA software | Detailed figures |
| 2 | AVGO | Broadcom | Compute and accelerator chips | Custom AI accelerators and Ethernet switching | Detailed figures |
| 3 | AMD | Advanced Micro Devices | Compute and accelerator chips | Instinct GPUs and EPYC server CPUs | Detailed figures |
| 4 | MRVL | Marvell Technology | Compute and accelerator chips | Custom silicon and optical interconnect | Detailed figures |
| 5 | ARM | Arm Holdings | Compute and accelerator chips | CPU designs licensed into AI servers | Key figures |
| 6 | INTC | Intel | Compute and accelerator chips | Xeon server CPUs and contract foundry | Key figures |
| 7 | QCOM | Qualcomm | Compute and accelerator chips | Custom inference silicon; moving into data centers | Key figures |
| 8 | MPWR | Monolithic Power Systems | Compute and accelerator chips | Power-delivery chips for AI boards | Profile |
| 9 | MU | Micron Technology | Memory and storage | DRAM and high-bandwidth memory (HBM) | Detailed figures |
| 10 | SKHY | SK hynix (ADR) | Memory and storage | HBM leader; Nasdaq ADR since July 2026 | Price snapshot |
| 11 | SNDK | Sandisk | Memory and storage | NAND flash and data center SSDs | Key figures |
| 12 | STX | Seagate Technology | Memory and storage | High-capacity hard drives | Price snapshot |
| 13 | WDC | Western Digital | Memory and storage | Hard drives for cloud data centers | Profile |
| 14 | TSM | Taiwan Semiconductor Manufacturing (ADR) | Foundry, equipment and chip design | Leading-edge contract chip manufacturing | Detailed figures |
| 15 | ASML | ASML Holding | Foundry, equipment and chip design | Sole supplier of EUV lithography | Key figures |
| 16 | AMAT | Applied Materials | Foundry, equipment and chip design | Deposition, etch and process equipment | Profile |
| 17 | LRCX | Lam Research | Foundry, equipment and chip design | Etch and deposition for memory and logic | Key figures |
| 18 | KLAC | KLA | Foundry, equipment and chip design | Inspection and metrology | Key figures |
| 19 | SNPS | Synopsys | Foundry, equipment and chip design | Chip design software and IP | Profile |
| 20 | CDNS | Cadence Design Systems | Foundry, equipment and chip design | EDA software and hardware emulation | Profile |
| 21 | AMKR | Amkor Technology | Foundry, equipment and chip design | Advanced packaging and test | Profile |
| 22 | TER | Teradyne | Foundry, equipment and chip design | Test systems for AI chips and HBM | Profile |
| 23 | ONTO | Onto Innovation | Foundry, equipment and chip design | Inspection and lithography for packaging | Price snapshot |
| 24 | ANET | Arista Networks | Networking, optics and connectivity | Ethernet switching for AI clusters | Detailed figures |
| 25 | CSCO | Cisco Systems | Networking, optics and connectivity | Silicon One systems and optics | Key figures |
| 26 | CRDO | Credo Technology | Networking, optics and connectivity | Active electrical cables and connectivity chips | Detailed figures |
| 27 | ALAB | Astera Labs | Networking, optics and connectivity | PCIe and fabric switches for AI racks | Key figures |
| 28 | LITE | Lumentum | Networking, optics and connectivity | Lasers and optical transceivers | Price snapshot |
| 29 | COHR | Coherent | Networking, optics and connectivity | Optical transceivers and lasers | Price snapshot |
| 30 | CIEN | Ciena | Networking, optics and connectivity | Optical systems linking data centers | Profile |
| 31 | GLW | Corning | Networking, optics and connectivity | Optical fiber and connectivity | Profile |
| 32 | APH | Amphenol | Networking, optics and connectivity | Connectors and cable assemblies | Profile |
| 33 | FN | Fabrinet | Networking, optics and connectivity | Optical component manufacturing | Profile |
| 34 | MTSI | MACOM Technology | Networking, optics and connectivity | Analog and optical chips for links | Price snapshot |
| 35 | SMTC | Semtech | Networking, optics and connectivity | Signal-integrity chips for links | Price snapshot |
| 36 | DELL | Dell Technologies | Servers and systems | AI servers, storage and PCs | Key figures |
| 37 | SMCI | Super Micro Computer | Servers and systems | AI server and rack systems | Key figures |
| 38 | CLS | Celestica | Servers and systems | Switches and AI server manufacturing | Key figures |
| 39 | HPE | Hewlett Packard Enterprise | Servers and systems | AI servers, supercomputers, networking | Profile |
| 40 | JBL | Jabil | Servers and systems | Manufacturing for cloud infrastructure | Profile |
| 41 | TSSI | TSS | Servers and systems | Rack integration services | Detailed figures |
| 42 | MSFT | Microsoft | Hyperscalers and platforms | Azure, Copilot and OpenAI partnership | Detailed figures |
| 43 | GOOGL | Alphabet | Hyperscalers and platforms | Google Cloud, TPUs and Gemini | Detailed figures |
| 44 | AMZN | Amazon | Hyperscalers and platforms | AWS, Trainium chips and Bedrock | Detailed figures |
| 45 | META | Meta Platforms | Hyperscalers and platforms | AI-driven ads and AI agents | Detailed figures |
| 46 | ORCL | Oracle | Hyperscalers and platforms | OCI capacity for AI labs | Detailed figures |
| 47 | AAPL | Apple | Hyperscalers and platforms | On-device AI on Apple silicon | Profile |
| 48 | TSLA | Tesla | Hyperscalers and platforms | Autonomy software and robotics | Profile |
| 49 | BABA | Alibaba Group (ADR) | Hyperscalers and platforms | Alibaba Cloud and Qwen models | Profile |
| 50 | CRWV | CoreWeave | Neoclouds and data center operators | GPU cloud for AI labs | Detailed figures |
| 51 | NBIS | Nebius Group | Neoclouds and data center operators | AI cloud in Europe and the US | Detailed figures |
| 52 | IREN | IREN | Neoclouds and data center operators | AI cloud built on bitcoin-mining sites | Detailed figures |
| 53 | APLD | Applied Digital | Neoclouds and data center operators | AI data center developer and landlord | Detailed figures |
| 54 | GLXY | Galaxy Digital | Neoclouds and data center operators | Helios data center campus plus digital assets | Detailed figures |
| 55 | WULF | TeraWulf | Neoclouds and data center operators | Data center leasing to AI tenants | Detailed figures |
| 56 | CORZ | Core Scientific | Neoclouds and data center operators | Colocation capacity for AI tenants | Detailed figures |
| 57 | CIFR | Cipher Mining | Neoclouds and data center operators | Mining sites converted to HPC leases | Profile |
| 58 | HUT | Hut 8 | Neoclouds and data center operators | Power-dense sites for AI and mining | Profile |
| 59 | RIOT | Riot Platforms | Neoclouds and data center operators | Powered land leased to AI tenants | Detailed figures |
| 60 | MARA | MARA Holdings | Neoclouds and data center operators | Bitcoin miner developing power sites | Detailed figures |
| 61 | SHAZ | SharonAI Holdings | Neoclouds and data center operators | Early-stage AI cloud, Asia-Pacific | Detailed figures |
| 62 | DOCN | DigitalOcean | Neoclouds and data center operators | Developer cloud adding GPU capacity | Profile |
| 63 | EQIX | Equinix | Neoclouds and data center operators | Colocation and interconnection REIT | Profile |
| 64 | DLR | Digital Realty | Neoclouds and data center operators | Hyperscale and colocation data center REIT | Key figures |
| 65 | PLTR | Palantir Technologies | Enterprise software and AI applications | AIP platform for enterprises and government | Detailed figures |
| 66 | NOW | ServiceNow | Enterprise software and AI applications | Workflow automation and AI agents | Detailed figures |
| 67 | CRM | Salesforce | Enterprise software and AI applications | CRM with Agentforce AI agents | Detailed figures |
| 68 | SNOW | Snowflake | Enterprise software and AI applications | Data cloud and AI agents on enterprise data | Key figures |
| 69 | CRWD | CrowdStrike | Enterprise software and AI applications | AI-assisted endpoint and cloud security | Detailed figures |
| 70 | PANW | Palo Alto Networks | Enterprise software and AI applications | Network, cloud and AI security | Profile |
| 71 | IBM | IBM | Enterprise software and AI applications | watsonx, Red Hat and AI consulting | Key figures |
| 72 | ADBE | Adobe | Enterprise software and AI applications | Firefly generative models in Creative Cloud | Profile |
| 73 | DDOG | Datadog | Enterprise software and AI applications | Observability for AI workloads | Profile |
| 74 | NET | Cloudflare | Enterprise software and AI applications | Edge network and AI inference | Profile |
| 75 | APP | AppLovin | Enterprise software and AI applications | AI-driven advertising engine | Profile |
| 76 | TEM | Tempus AI | Enterprise software and AI applications | AI in diagnostics and clinical data | Profile |
| 77 | SOUN | SoundHound AI | Enterprise software and AI applications | Voice AI and customer-service agents | Detailed figures |
| 78 | BBAI | BigBear.ai | Enterprise software and AI applications | Decision intelligence for defense | Detailed figures |
| 79 | AI | C3.ai | Enterprise software and AI applications | Enterprise AI applications | Detailed figures |
| 80 | CEG | Constellation Energy | Power generation | Nuclear power under hyperscaler contracts | Detailed figures |
| 81 | VST | Vistra | Power generation | Texas nuclear and gas generation | Detailed figures |
| 82 | TLN | Talen Energy | Power generation | PJM generation with data center deals | Key figures |
| 83 | NRG | NRG Energy | Power generation | Generation and retail power in Texas | Profile |
| 84 | BE | Bloom Energy | Power generation | On-site fuel-cell power | Price snapshot |
| 85 | OKLO | Oklo | Power generation | Pre-commercial small nuclear reactors | Key figures |
| 86 | VRT | Vertiv | Electrical, cooling and grid equipment | Power and liquid cooling for data centers | Detailed figures |
| 87 | ETN | Eaton | Electrical, cooling and grid equipment | Electrical distribution and power management | Detailed figures |
| 88 | GEV | GE Vernova | Electrical, cooling and grid equipment | Gas turbines and grid equipment | Detailed figures |
| 89 | NVT | nVent Electric | Electrical, cooling and grid equipment | Enclosures and liquid cooling | Profile |
| 90 | MOD | Modine Manufacturing | Electrical, cooling and grid equipment | Data center cooling systems | Profile |
| 91 | CAT | Caterpillar | Electrical, cooling and grid equipment | Engines and turbines for on-site power | Profile |
| 92 | AMSC | American Superconductor | Electrical, cooling and grid equipment | Grid and power-quality equipment | Detailed figures |
| 93 | HMDPF | Hammond Power Solutions | Electrical, cooling and grid equipment | Dry-type transformers | Detailed figures |
| 94 | PPIH | Perma-Pipe International | Electrical, cooling and grid equipment | Pre-insulated piping incl. cooling | Detailed figures |
| 95 | PWR | Quanta Services | Construction and engineering | Grid and power construction | Detailed figures |
| 96 | EME | EMCOR Group | Construction and engineering | Electrical and mechanical contracting | Profile |
| 97 | FIX | Comfort Systems USA | Construction and engineering | Mechanical and modular construction | Profile |
| 98 | AMRC | Ameresco | Construction and engineering | Energy infrastructure projects | Detailed figures |
| 99 | MEC | Mayville Engineering | Construction and engineering | Fabrication for data center equipment | Detailed figures |
| 100 | MTRX | Matrix Service | Construction and engineering | Energy and utility construction | Detailed figures |
Detailed figures: several metrics from the latest earnings release or filing. Key figures: headline results from the latest release. Price snapshot: the November 11 intraday move plus a business profile. Profile: the company’s role in AI and what to track; no current-quarter figures were verified for this edition.
Nos. 1–8, 8 companies
Compute and accelerator chips
Accelerators are where most AI spending lands first. NVIDIA’s Data Center segment reported about $89bn of revenue in a single quarter. Broadcom and Marvell co-design custom accelerators with individual hyperscalers, and AMD competes with GPUs of its own. CPU suppliers such as Intel, Arm and Qualcomm benefit because every accelerator rack also needs host processors.
The companies define their AI revenue differently. NVIDIA reports a Data Center platform segment, AMD’s Data Center segment includes server CPUs, and Broadcom’s AI semiconductor figure is a management definition. Fiscal quarters also end on different dates. The growth rates below show momentum, not market share.
AI-related revenue growth, by each company’s own definition
Year-over-year growth, latest reported quarter
NVDANVIDIA
GPUs, networking and CUDA software
Designs the GPUs, rack-scale systems, networking and CUDA software used in most large AI training clusters and a large share of inference. Its Data Center segment is the largest single revenue pool in this guide.
What to watch: Operating cash flow of $24.08bn equaled about 40.3% of net income ($59.69bn). Net income included $7.77bn of equity-security gains, and receivables stood at $63.06bn at quarter end, so cash conversion is worth checking each quarter. Gene Munster, quoted by Benzinga, describes NVIDIA as a full infrastructure platform rather than a chip vendor.
Q2 FY2027, quarter ended July 26, 2026
| Revenue | $96.22bn (up 106% YoY) |
| Data Center revenue | ~$89bn (up 117% YoY) |
| Gross margin | 75% |
| Free cash flow (company definition) | $21.34bn |
| Q3 FY2027 revenue guidance, midpoint | ~$108bn |
Sources: Nvidia fiscal second-quarter company earnings release; Munster outlines Nvidia platform growth thesis
AVGOBroadcom
Custom AI accelerators and Ethernet switching
Co-designs custom AI accelerators with hyperscalers and supplies the Ethernet switching chips that connect large clusters. It also owns a large infrastructure-software business built around VMware.
What to watch: AI semiconductor sales were about 56.4% of total company revenue. Shares fell after the September report because total fourth-quarter guidance landed slightly below consensus, a reminder that growth and the stock reaction can diverge. Broadcom appeared on Cantor Fitzgerald's November semiconductor list.
Q3 FY2026, quarter ended August 2, 2026
| Revenue | $29.59bn (up 86% YoY) |
| AI semiconductor revenue (management-defined) | ~$16.7bn (up 221% YoY) |
| Free cash flow | $13.66bn |
| Q4 FY2026 revenue guidance | ~$34.8bn |
| Q4 FY2026 AI semiconductor guidance | ~$21.7bn |
Sources: Broadcom fiscal third-quarter company earnings release; Broadcom growth meets higher investor expectations; Analysts weigh semiconductor buying opportunities after steep declines
AMDAdvanced Micro Devices
Instinct GPUs and EPYC server CPUs
Sells Instinct accelerators and EPYC server processors. Its Data Center segment combines both, so the reported growth is not a pure accelerator figure.
What to watch: CEO Lisa Su told investors AMD and its customers are coordinating land, power and site readiness for planned 2027 deployments. AMD appeared on both the Cantor Fitzgerald list and Shay Boloor's post-election rebound list. Quarterly free cash flow was well below operating income.
Q3 2026, quarter ended September 26, 2026
| Revenue | $13.38bn (up 45% YoY) |
| Data Center revenue | $8.55bn (up 97% YoY) |
| Data Center operating income | $2.88bn |
| Free cash flow | $554m |
| Q4 2026 revenue guidance, midpoint | ~$17bn |
Sources: AMD third-quarter company earnings release; AMD discusses infrastructure readiness for future deployments; Strategist selects AI stocks following election volatility
MRVLMarvell Technology
Custom silicon and optical interconnect
Builds custom AI chips for hyperscalers and the electro-optical connectivity used inside AI data centers. On November 2, 2026 it announced an all-stock agreement to acquire Lumentum.
What to watch: Management targets roughly $30bn of custom revenue in fiscal 2031; that is a target, not recognized revenue. The Lumentum consideration is fixed at 4.5 Marvell shares per Lumentum share, so its dollar value moves with Marvell's stock, and closing remains conditional.
Q2 FY2027, quarter ended August 1, 2026
| Revenue | $2.74bn (up 37% YoY) |
| Data Center revenue | $2.17bn (up 46% YoY) |
| Operating cash flow | $605.5m |
| Q3 FY2027 revenue guidance, midpoint | ~$3.1bn |
| Lumentum deal, implied enterprise value | ~$115bn |
November 11, 2026, late-morning snapshot: $171.13, up 10.84% intraday. Historical, not a current quote.
Sources: Marvell Technology, Inc. Reports Second Quarter of Fiscal Year 2027 Financial Results; Marvell projects growth in custom AI chips; Marvell and Lumentum definitive transaction announcement; Marvell and Lumentum transaction analysis; CoreWeave results trigger widespread AI stock rally
ARMArm Holdings
CPU designs licensed into AI servers
Licenses the CPU architecture and compute subsystems used in hyperscaler server chips and is now selling its own AGI CPU. It earns licensing fees up front and royalties as chips ship.
What to watch: Data center royalties doubled year over year, but total royalty growth slowed to 8% as smartphone demand weakened, so licensing carried the quarter. Selling its own CPU means Arm now competes with some of its licensees.
Q2 FY2027, quarter ended September 30, 2026
| Revenue | $1.44bn (up 27% YoY) |
| Licensing and other revenue | $773m (up 50% YoY) |
| Royalty revenue | $670m (up 8% YoY) |
| Q3 FY2027 revenue guidance | $1.54bn, plus or minus $50m |
| AGI CPU revenue outlook | Up to $2bn across FY2027 and FY2028 |
November 11, 2026, late-morning snapshot: $202.32, up 11.47% intraday. Historical, not a current quote.
Sources: Arm Q2 FYE27 results; Neoteo: Arm Q2 FY2027 figures and guidance; CoreWeave results trigger widespread AI stock rally
INTCIntel
Xeon server CPUs and contract foundry
Supplies Xeon processors that host AI accelerators in servers and is building a contract manufacturing business, Intel Foundry.
What to watch: Management expects the PC slowdown to last at least through the first half of 2027, and the full fourth-quarter guidance range sits below third-quarter revenue. Server CPU demand tied to AI clusters is the main source of growth.
Q3 2026, quarter ended September 2026
| Revenue | $16.5bn (up 21% YoY) |
| Data Center and AI revenue | $7.3bn (up 78% YoY) |
| Intel Foundry revenue | $6.7bn (up 58% YoY, includes intersegment sales) |
| Operating cash flow | $5.1bn |
| Q4 2026 revenue guidance | $15.0−16.0bn |
Sources: Intel Q3 2026 results release
QCOMQualcomm
Custom inference silicon; moving into data centers
Best known for smartphone processors and modems. It is entering data center AI with custom inference silicon, CPUs and optical connectivity, including a multi-generation collaboration with Amazon.
What to watch: The $5bn target depends on a ramp still in early production. The Amazon arrangement includes warrants tied to potential purchases, which are not guaranteed orders. Investors are weighing that ramp against a shrinking handset business.
Q4 FY2026, quarter ended September 27, 2026
| Revenue | $10.32bn (down 8% YoY) |
| Handset chip revenue | $5.14bn (down 26% YoY) |
| Data center revenue expected in Q1 FY2027 | At least $650m |
| Fiscal 2027 data center revenue target | $5bn |
Sources: Benzinga: Qualcomm Q4 highlights; Securities.io: Qualcomm data center target
MPWRMonolithic Power Systems
Power-delivery chips for AI boards
Designs power-management chips that convert and regulate the power delivered to AI accelerators, CPUs and server boards. Higher accelerator power draw raises the amount of power silicon needed per rack.
What to watch: Track the share of revenue from data center customers and how much depends on a small number of accelerator platforms.
Nos. 9–13, 5 companies
Memory and storage
Each AI accelerator sits beside stacks of high-bandwidth memory, and inference workloads lean heavily on fast flash storage. Supply has not kept up. Micron reported a 86.8% gross margin for its fiscal fourth quarter and guided first-quarter revenue to about $61.5bn; Sandisk reported an 85.0% gross margin and revenue up 378% from a year earlier.
Memory has always been cyclical, and these margins reflect a shortage rather than a permanent change in the business. The useful signals are long-term supply agreements, capacity additions across the industry and the share of revenue coming from data centers, which is rising quickly.
Data centers account for a growing share of memory revenue
Share of revenue from data-center-facing units or end markets
MUMicron Technology
DRAM and high-bandwidth memory (HBM)
One of three large DRAM producers and a supplier of the high-bandwidth memory (HBM) stacked beside AI accelerators. It also sells data center SSDs.
What to watch: Memory is a cyclical business and current margins reflect tight supply. Cantor Fitzgerald included Micron in its November list while acknowledging that low multiples on cyclical profits can turn into value traps. Shares rose about 13% on November 11 as CoreWeave's outlook eased spending concerns.
Q4 FY2026, quarter ended September 3, 2026
| Revenue | $54.23bn |
| Cloud Memory Business Unit revenue | $16.28bn |
| Gross margin (GAAP) | 86.8% |
| Fiscal 2026 revenue | $133.2bn |
| Q1 FY2027 revenue guidance, midpoint | ~$61.5bn |
November 11, 2026, late-morning snapshot: $815.18, up 12.42% intraday. Historical, not a current quote.
Sources: Micron Technology, Inc. Reports Record Fiscal Fourth-Quarter and Full-Year 2026 Results; Micron benefits from improved AI infrastructure sentiment; Analysts weigh semiconductor buying opportunities after steep declines; CoreWeave results trigger widespread AI stock rally
SKHYSK hynix (ADR)
HBM leader; Nasdaq ADR since July 2026
South Korea's largest memory maker and a leading HBM supplier to NVIDIA. Its American depositary receipts began trading on Nasdaq on July 10, 2026, after pricing at $149 each.
What to watch: The common shares also trade in Seoul (000660), and the ADR and local prices can diverge. The ADR is the same business as the Korean listing, not a separate entity.
November 11, 2026, late-morning snapshot: $143.83, up 10.92% intraday. Historical, not a current quote.
Sources: Kyunghyang Shinmun: SK hynix lists ADRs on Nasdaq; New Straits Times: SK hynix ADR pricing; CoreWeave results trigger widespread AI stock rally
SNDKSandisk
NAND flash and data center SSDs
Makes NAND flash and solid-state drives. It separated from Western Digital in 2025, and data center SSDs used for inference, caching and data staging now drive most of its growth.
What to watch: An 8-for-1 stock split is scheduled to take effect on November 19, 2026, so the pre-split price in the November 11 snapshot will not match post-split quotes. Management said roughly half of fiscal 2027 bits are already covered by long-term agreements.
Q1 FY2027, quarter ended October 2, 2026
| Revenue | $11.03bn (up 378% YoY) |
| Data center revenue | $4.80bn (up 61% from prior quarter) |
| Gross margin (GAAP) | 85.0% |
| Q2 FY2027 revenue guidance | $12.2−12.6bn |
November 11, 2026, late-morning snapshot: $991.90, up 15.33% intraday. Historical, not a current quote.
Sources: Sandisk fiscal Q1 2027 results release; MarketBeat: Sandisk Q1 call highlights; 24/7 Wall St.: Sandisk results and stock split; CoreWeave results trigger widespread AI stock rally
STXSeagate Technology
High-capacity hard drives
Makes hard-disk drives. High-capacity drives hold most of the data that AI systems train on and generate, and Seagate's heat-assisted (HAMR) drives raise capacity per unit.
What to watch: Track exabyte shipments, pricing and the pace of the HAMR transition.
November 11, 2026, late-morning snapshot: $557.78, up 11.19% intraday. Historical, not a current quote.
Sources: CoreWeave results trigger widespread AI stock rally
WDCWestern Digital
Hard drives for cloud data centers
Makes high-capacity hard drives sold mostly to cloud data center operators, after separating its flash business into Sandisk in 2025.
What to watch: Track cloud exabyte demand and pricing; the business is now concentrated in hard drives.
Nos. 14–23, 10 companies
Foundry, equipment and chip design
Nearly every AI chip in this guide is manufactured at TSMC’s leading-edge nodes using equipment from a short list of suppliers. ASML is the only source of EUV lithography; Applied Materials, Lam Research and KLA supply deposition, etch and inspection tools; Synopsys and Cadence sell the design software; Amkor and Teradyne handle packaging and test.
Orders in this layer follow chipmakers’ capacity plans, which currently point higher. Three of the four companies with recent guidance expect double-digit sequential revenue growth. Lam and KLA both expect China’s share of revenue to fall in the December quarter.
Next-quarter guidance against the latest quarter
Guidance midpoint indexed to the latest reported quarter (= 100)
TSMTaiwan Semiconductor Manufacturing (ADR)
Leading-edge contract chip manufacturing
The dominant contract manufacturer of leading-edge chips, including AI accelerators and custom silicon designed by NVIDIA, AMD, Broadcom and hyperscalers. Its foundry revenue serves many end markets, not only AI.
What to watch: Benzinga reported that TSMC's board authorized investments in Anthropic and OpenAI. Results are reported in Taiwan dollars, so US-dollar growth differs from local-currency growth.
Q3 2026, quarter ended September 30, 2026
| Revenue (US dollars) | ~$46.7bn (up 41.2% YoY) |
| Revenue (NT dollars) | NT$1.49tn (up 50.9% YoY) |
| Gross margin | 66.4% |
| 7nm-and-below share of wafer revenue | 79% |
| October 2026 revenue | ~NT$586.9bn (up 59.7% YoY) |
| Q4 2026 revenue guidance | $52.3−54.3bn |
Sources: TSMC Reports Third Quarter EPS of NT$29.43; TSMC October consolidated revenue report; TSMC shares respond to AI investment and revenue growth
ASMLASML Holding
Sole supplier of EUV lithography
The only supplier of extreme ultraviolet (EUV) lithography systems, which are required to print the most advanced logic and memory chips.
What to watch: ASML has said it plans to raise low-NA EUV and DUV immersion capacity by 30% in 2027 and is studying a further increase for 2028. China's share of sales and export controls remain the main external variables. Cantor Fitzgerald included ASML in its November list.
Q3 2026, quarter ended September 27, 2026
| Net sales | €11.7bn (up 55% YoY) |
| Gross margin | 57.5% |
| Net income | €5.0bn |
| Q4 2026 net sales guidance | €14.2−15.2bn |
| Full-year 2026 net sales guidance | €44−45bn |
Sources: ASML Q3 2026 results; ASML Q3 2026 press release; Analysts weigh semiconductor buying opportunities after steep declines
AMATApplied Materials
Deposition, etch and process equipment
The largest US maker of chip-manufacturing equipment, covering deposition, etch, ion implant and process control. Spending on leading-edge logic, HBM and advanced packaging drives demand for its tools.
What to watch: Applied Materials was on Cantor Fitzgerald's November 9 semiconductor list. Track China revenue share and orders tied to gate-all-around transistors and HBM.
Sources: Analysts weigh semiconductor buying opportunities after steep declines
LRCXLam Research
Etch and deposition for memory and logic
Supplies etch and deposition equipment, with heavy exposure to memory makers expanding HBM and advanced NAND capacity.
What to watch: Memory accounted for 46% of systems revenue. China was 35% of September-quarter revenue, and management expects that share to fall significantly in the December quarter. Lam was on Cantor Fitzgerald's November list.
September 2026 quarter (fiscal Q1 2027)
| Revenue | $8.22bn (up 54% YoY) |
| GAAP gross margin | 52.3% |
| GAAP operating margin | 40.0% |
| December 2026 quarter revenue guidance | $8.6bn, plus or minus $0.4bn |
Sources: Lam Research September 2026 quarter release (SEC); MarketBeat: Lam Research call highlights; Analysts weigh semiconductor buying opportunities after steep declines
KLACKLA
Inspection and metrology
Leads in process control: the inspection and measurement tools chipmakers use to find defects. Larger AI chips and advanced packaging raise the amount of inspection per wafer.
What to watch: KLA completed a 10-for-1 stock split effective June 11, 2026, so per-share history needs split adjustment. KLA expects China to decline as a share of revenue in the December quarter. KLA was on Cantor Fitzgerald's November list.
Q1 FY2027, quarter ended September 30, 2026
| Revenue | $4.14bn (up 29% YoY) |
| GAAP net income | $1.55bn |
| Q2 FY2027 revenue guidance | $4.7bn, plus or minus $0.2bn |
Sources: iConnect007: KLA fiscal Q1 2027 results; Securities.io: KLA fiscal Q1 detail; Analysts weigh semiconductor buying opportunities after steep declines
SNPSSynopsys
Chip design software and IP
Sells electronic design automation (EDA) software and licensed silicon IP used to design AI chips, and added engineering simulation through its acquisition of Ansys.
What to watch: Track design-starts activity, China exposure and growth in its IP business.
CDNSCadence Design Systems
EDA software and hardware emulation
Sells EDA software plus hardware emulation and prototyping systems that chip designers use to verify very large AI processors before manufacturing.
What to watch: Track emulation hardware demand, which tends to rise when large new chip designs are in development.
AMKRAmkor Technology
Advanced packaging and test
Provides outsourced chip packaging and test, including the advanced packaging used to combine accelerators with HBM. It is building an advanced packaging site in Arizona.
What to watch: Track advanced packaging capacity, customer concentration and the timing of the Arizona site.
TERTeradyne
Test systems for AI chips and HBM
Makes automated test equipment for semiconductors, including testers used for AI accelerators and high-bandwidth memory, and owns industrial robotics businesses.
What to watch: Track compute and memory test demand separately from the robotics segment.
ONTOOnto Innovation
Inspection and lithography for packaging
Supplies process-control, inspection and lithography tools, with growing exposure to the advanced packaging steps used for AI accelerators.
What to watch: Track advanced packaging orders and customer concentration.
November 11, 2026, late-morning snapshot: $217.65, up 10.19% intraday. Historical, not a current quote.
Sources: CoreWeave results trigger widespread AI stock rally
Nos. 24–35, 12 companies
Networking, optics and connectivity
Large AI clusters only work if thousands of accelerators can exchange data quickly, which makes switches, optical transceivers, cables and signal-conditioning chips a growing share of data center budgets. Arista and Cisco sell switches; Credo, Astera Labs, Marvell, MACOM and Semtech sell connectivity silicon; Lumentum, Coherent and Fabrinet make optical components; Corning and Amphenol supply fiber and connectors.
Marvell’s proposed all-stock acquisition of Lumentum, announced November 2 at an implied enterprise value of about $115bn, would combine custom silicon with optics. Across chip and networking suppliers, the fastest growers also tend to earn high gross margins.
Revenue growth and gross margin across chip and networking suppliers
Latest reported quarter; growth is year over year
ANETArista Networks
Ethernet switching for AI clusters
Sells high-speed Ethernet switches and software used to build AI back-end and front-end networks, with hyperscalers as its largest customers.
What to watch: Management expects existing networking applications to drive near-term revenue and does not expect scale-up networking to contribute materially until 2028. The 2027 AI target is a management target, not recognized revenue.
Q3 2026, quarter ended September 30, 2026
| Revenue | $3.66bn (up 58.5% YoY) |
| Gross margin (GAAP) | 63.6% |
| Net income | $1.56bn |
| Q4 2026 revenue guidance | $3.9−4.0bn |
| Calendar 2027 AI fabrics revenue target | ~$7bn |
Sources: Arista Networks, Inc. Reports Third Quarter 2026 Financial Results; Arista outlines timing of AI networking opportunities
CSCOCisco Systems
Silicon One systems and optics
Sells networking systems built on its Silicon One chips, Acacia optics and security software. Hyperscaler AI infrastructure has become a measurable share of its business.
What to watch: Hyperscaler AI infrastructure was about 6% of fiscal 2026 revenue. Management said roughly 60% of those orders were Silicon One systems and 40% optics, and hardware mix weighed on gross margin.
Fiscal 2026, year ended July 2026
| Hyperscaler AI infrastructure orders, FY2026 | $9.3bn |
| Q4 FY2026 revenue | $17.3bn (up 18% YoY) |
| Expected hyperscaler AI infrastructure revenue, FY2027 | ~$7.5bn |
| Fiscal 2027 revenue guidance | $72.2−73.4bn |
Sources: MarketBeat: Cisco Q4 FY2026 call highlights; Pulse 2.0: Cisco AI infrastructure orders
CRDOCredo Technology
Active electrical cables and connectivity chips
Sells active electrical cables, SerDes and optical DSP chips that move data between servers and switches inside AI racks.
What to watch: The release did not include a cash-flow statement, so cash conversion could not be checked. Credo appeared on Shay Boloor's November 5 rebound list.
Q1 FY2027, quarter ended August 1, 2026
| Revenue | $479.0m (up 114.7% YoY) |
| Gross margin (GAAP) | 64.5% |
| Net income (GAAP) | $129.4m |
| Q2 FY2027 revenue guidance | $525−535m |
November 11, 2026, late-morning snapshot: $144.36, up 11.21% intraday. Historical, not a current quote.
Sources: Credo Technology Group Holding Ltd Reports First Quarter of Fiscal Year 2027 Financial Results; Strategist selects AI stocks following election volatility; CoreWeave results trigger widespread AI stock rally
ALABAstera Labs
PCIe and fabric switches for AI racks
Designs connectivity chips for rack-scale AI systems, including Scorpio fabric switches, Aries retimers and Taurus cable modules.
What to watch: Scorpio fabric switches became the largest product family in the quarter. Customer concentration and stock-based compensation are the main points to monitor.
Q3 2026, quarter ended September 30, 2026
| Revenue | $584.9m (up 154% YoY) |
| GAAP gross margin | 72.3% |
| GAAP operating margin | 30.6% |
| Q4 2026 revenue guidance | $730−750m |
Sources: Astera Labs Q3 2026 release (SEC); Earnings Whispers: Astera Labs results
LITELumentum
Lasers and optical transceivers
Makes lasers, optical components and transceivers used in AI data center links. Marvell agreed on November 2, 2026 to acquire it in an all-stock deal.
What to watch: The reference value implied a premium of about 23.9% at announcement, but the dollar value floats with Marvell's share price. Lumentum holders would own about 33% of the combined company. Closing remains conditional.
Q1 FY2027 (limited data from transaction coverage)
| Revenue | $1.26bn |
| Q2 FY2027 revenue guidance | $1.6−1.6bn |
| Deal terms | 4.5 Marvell shares per Lumentum share |
| Reference value per share at announcement | ~$1,132 |
November 11, 2026, late-morning snapshot: $664.49, up 13.47% intraday. Historical, not a current quote.
Sources: Marvell and Lumentum definitive transaction announcement; Marvell and Lumentum transaction analysis; CoreWeave results trigger widespread AI stock rally
COHRCoherent
Optical transceivers and lasers
Makes optical transceivers, lasers and engineered materials used in data center networking, alongside industrial laser businesses.
What to watch: Track datacom transceiver growth and the transition to 1.6T optics.
November 11, 2026, late-morning snapshot: $239.28, up 11.46% intraday. Historical, not a current quote.
Sources: CoreWeave results trigger widespread AI stock rally
CIENCiena
Optical systems linking data centers
Sells optical networking systems and coherent modules used to connect data centers to each other and to cloud regions.
What to watch: Track cloud-provider orders for data center interconnect.
GLWCorning
Optical fiber and connectivity
Makes optical fiber, cable and connectivity products that wire data centers internally and connect campuses.
What to watch: Corning was among the suppliers in Benzinga's November 10 report on a broad selloff in AI infrastructure suppliers, which showed that strong demand did not prevent sharp share declines.
Sources: AI infrastructure suppliers face broad selling pressure
APHAmphenol
Connectors and cable assemblies
Supplies high-speed connectors, cable assemblies and power interconnects used inside AI server racks.
What to watch: Track IT datacom sales growth relative to the rest of the business.
FNFabrinet
Optical component manufacturing
A contract manufacturer of optical communications components and modules for networking and data center customers.
What to watch: Track customer concentration and capacity expansion.
MTSIMACOM Technology
Analog and optical chips for links
Designs analog, RF and optical semiconductors, including components used in high-speed data center optical links.
What to watch: Track data center revenue as a share of the total.
November 11, 2026, late-morning snapshot: $251.32, up 10.96% intraday. Historical, not a current quote.
Sources: CoreWeave results trigger widespread AI stock rally
SMTCSemtech
Signal-integrity chips for links
Designs analog and mixed-signal chips, including signal-integrity products used in data center optical and copper connections.
What to watch: Track data center product growth against its IoT and industrial lines.
November 11, 2026, late-morning snapshot: $126.83, up 11.75% intraday. Historical, not a current quote.
Sources: CoreWeave results trigger widespread AI stock rally
Nos. 36–41, 6 companies
Servers and systems
Server makers assemble accelerators, CPUs, memory, networking and cooling into finished racks. This layer has added the most revenue in dollar terms, but margins are thin: Super Micro’s gross margin was 12.7% in its latest quarter, down from 17.5% the quarter before. Dell’s order book shows how far demand is running ahead of shipments.
Dell AI server orders, revenue and backlog
Q2 FY2027, quarter ended July 31, 2026
Super Micro quarterly net sales
Quarters ended September 2025, June 2026 and September 2026
DELLDell Technologies
AI servers, storage and PCs
Builds AI-optimized servers for cloud providers, neoclouds and enterprises, along with storage and PCs.
What to watch: Orders and backlog are not recognized revenue; converting them depends on supply of accelerators, memory and power at customer sites. Dell raised its fiscal 2027 AI server revenue forecast to about $74bn.
Q2 FY2027, quarter ended July 31, 2026
| Revenue | $47.0bn (up 58% YoY) |
| AI-optimized server revenue | $16.4bn (up 100% YoY) |
| AI server orders | $60.9bn |
| AI server backlog at quarter end | $95bn |
| Fiscal 2027 revenue outlook | ~$192bn |
November 11, 2026, late-morning snapshot: $376.33, up 12.54% intraday. Historical, not a current quote.
Sources: Dell Q2 FY2027 release; StorageNewsletter: Dell fiscal 2Q27; Pulse 2.0: Dell outlook raised; CoreWeave results trigger widespread AI stock rally
SMCISuper Micro Computer
AI server and rack systems
Designs and assembles AI server and liquid-cooled rack systems built on NVIDIA and other accelerators.
What to watch: Results were preliminary and unaudited when released, which matters given the company's accounting history. Margins fell sharply as volume rose, and receivables and inventory absorbed cash.
Q1 FY2027, quarter ended September 30, 2026 (preliminary, unaudited)
| Net sales | $19.9bn (vs $5.0bn a year earlier) |
| Gross margin (GAAP) | 12.7% (17.5% prior quarter) |
| Cash used in operations | ($434m) |
| Fiscal 2027 net sales guidance | $72−82bn |
November 11, 2026, late-morning snapshot: $30.63, up 10.20% intraday. Historical, not a current quote.
Sources: Supermicro Q1 FY2027 release (SEC); Securities.io: Supermicro outlook; CoreWeave results trigger widespread AI stock rally
CLSCelestica
Switches and AI server manufacturing
Designs and manufactures network switches, servers and storage systems for hyperscalers and AI developers.
What to watch: Revenue is concentrated among a small number of hyperscale customers, and inventory rose $1.1bn in the quarter to about $4.5bn. Celestica appears on Benzinga's evergreen AI stock guide.
Q3 2026, quarter ended September 30, 2026
| Revenue | $5.83bn (up 83% YoY) |
| Connectivity and Cloud Solutions revenue | $4.87bn (up 102% YoY) |
| Q4 2026 revenue guidance | $6.275−6.575bn |
| 2027 revenue outlook | ~$40bn |
Sources: Celestica Q3 2026 release (SEC); Celestica Q3 2026 release and Q4 guidance; Evertiq: Celestica 2027 outlook; Earnings Whispers: Celestica Q3 review; Benzinga evergreen guide to AI stocks
HPEHewlett Packard Enterprise
AI servers, supercomputers, networking
Sells AI servers and Cray supercomputing systems, storage and networking to enterprises, governments and service providers.
What to watch: Track AI systems backlog and margins on AI server deals.
JBLJabil
Manufacturing for cloud infrastructure
An electronics manufacturing services company with a growing cloud and data center infrastructure business.
What to watch: Track the cloud and data center segment against slower consumer and industrial lines.
TSSITSS
Rack integration services
A small systems integrator that assembles and configures server racks. Procurement makes up most of its revenue, with integration services as the higher-margin growth line.
What to watch: Procurement was about 64.7% of quarterly revenue and carries lower margins than integration work. Nine-month revenue was down about 24% year over year. TSS appeared in Tim Melvin's November 3 small-cap list.
Q3 2026, quarter ended September 30, 2026
| Revenue | $50.1m (up ~20% YoY) |
| Systems integration revenue | $16.1m (up ~75% YoY) |
| Net income | $1.15m |
| FY2026 adjusted EBITDA guidance | $21−23m |
Sources: TSS third quarter 2026 results; Contributor identifies smaller AI infrastructure companies
Nos. 42–49, 8 companies
Hyperscalers and platforms
Microsoft, Alphabet, Amazon, Meta and Oracle are the largest buyers of AI infrastructure and the companies best placed to resell it as cloud services. Cloud growth has accelerated: Google Cloud revenue roughly doubled, Azure grew 48% and AWS 39%. Spending has grown faster still, and at Alphabet, Meta and Oracle it exceeded operating cash flow in the latest quarter.
The comparison keeps each company’s own capex measure. Microsoft’s free cash flow uses cash paid for equipment, while its $45.2bn headline capex includes finance leases. Meta includes finance-lease principal. Amazon reports cash flow on a trailing 12-month basis: ($42.36bn) of free cash flow over the year to September.
Operating cash flow and capital spending, latest quarter
US$ billions; free cash flow at right
2026 capital spending plans
Guidance ranges, US$ billions
MSFTMicrosoft
Azure, Copilot and OpenAI partnership
Runs Azure, one of the three largest cloud platforms, and sells AI features through Microsoft 365 Copilot and GitHub. It funds its data center expansion largely from operating cash flow.
What to watch: Cash spent on property and equipment used about 67.9% of quarterly operating cash flow, the lowest ratio among the large platforms in this guide. Benzinga reported in early November that Microsoft was reassessing some external computing contracts with neocloud providers and winding down an older-GPU lease with Oracle.
Q1 FY2027, quarter ended September 30, 2026
| Revenue | $92.28bn (up 19% YoY) |
| Azure revenue | $33.16bn (up 48% YoY) |
| Commercial remaining performance obligations | ~$677bn |
| Capex including finance leases | ~$45.2bn |
| Free cash flow (OCF less cash PP&E) | ~$18.6bn |
| Calendar 2026 capex guidance | ~$170bn |
Sources: Microsoft Announces First Quarter Results; Microsoft official fiscal first-quarter earnings discussion; Microsoft fiscal first-quarter earnings discussion; Microsoft reviews computing contracts with neocloud providers; Microsoft reportedly reduces older Oracle computing lease
GOOGLAlphabet
Google Cloud, TPUs and Gemini
Owns Google Search, Google Cloud and the Gemini models, and designs its own TPU accelerators, which it also sells as systems through Google Cloud.
What to watch: Quarterly capex was about 121.5% of operating cash flow, so the quarter's free cash flow turned negative while trailing-year free cash flow stayed positive. Benzinga reported that five of six listed analyst firms cut price targets after the quarter while largely keeping bullish ratings, citing softer Search and higher costs.
Q3 2026, quarter ended September 30, 2026
| Revenue | ~$127.6bn (up 25% YoY) |
| Google Cloud revenue | ~$30.7bn (up 103% YoY) |
| Google Cloud backlog | ~$561bn |
| Capital expenditures | ~$51.4bn |
| Free cash flow, quarter / trailing 12 months | (~$9.1bn) / ~$19.7bn |
| Calendar 2026 capex guidance | $195−205bn |
Sources: Alphabet official third-quarter earnings discussion; Alphabet third-quarter earnings discussion and transcript correction; Analysts cut Alphabet targets while largely retaining bullish ratings; Alphabet spending raises concerns about near-term margins
AMZNAmazon
AWS, Trainium chips and Bedrock
Runs AWS, the largest cloud platform by revenue, designs its own Trainium and Inferentia AI chips, and offers models through Bedrock.
What to watch: Management projected AWS growth above 40% in each of 2027 and 2028, a projection rather than guidance. Shares fell about 7.3% after hours on the report even as commentators praised the AWS acceleration.
Q3 2026, quarter ended September 30, 2026
| Net sales | $201.9bn (up 12% YoY) |
| AWS net sales | $45.98bn (up 39% YoY) |
| AWS operating income | ~$17.8bn |
| Free cash flow, trailing 12 months | ($42.36bn) |
| PP&E purchases net of proceeds, trailing 12 months | $210.7bn |
| Q4 2026 net sales guidance | $240−247bn |
Sources: Amazon third-quarter company earnings release; Amazon third-quarter earnings discussion; Commentators assess Amazon growth after earnings selloff
METAMeta Platforms
AI-driven ads and AI agents
Uses AI to rank content and target ads across Facebook, Instagram, WhatsApp and Threads, and builds its own models and AI agents. AI revenue is embedded in advertising rather than reported separately.
What to watch: Capital spending including lease principal was about 106.5% of operating cash flow. Ad impressions grew 10% and average price per ad grew 14%, which management links to AI ranking improvements.
Q3 2026, quarter ended September 30, 2026
| Revenue | $64.6bn (up 26% YoY) |
| Operating margin | 20% (after a $9.89bn litigation charge) |
| Capex including finance-lease principal | ~$34.9bn |
| Free cash flow | ($2.12bn) |
| Calendar 2026 capex guidance | $135−145bn |
| Q4 2026 revenue guidance | $73−76bn |
Sources: Meta third-quarter company earnings release; Meta third-quarter earnings discussion
ORCLOracle
OCI capacity for AI labs
Builds Oracle Cloud Infrastructure (OCI) capacity under large contracts with AI developers, alongside its database and applications business.
What to watch: About 49.2% of quarterly operating cash flow came from customer prepayments with a significant financing component. Bernstein, quoted by Benzinga, expects positive free cash flow in the second half of fiscal 2028; Steve Eisman has described a downside scenario tied to OpenAI's finances. Fiscal 2027 revenue guidance is at least ≥$90bn.
Q1 FY2027, quarter ended August 31, 2026
| Revenue | $19.34bn (up 30% YoY) |
| Cloud infrastructure revenue | $7.39bn (up 121% YoY) |
| Remaining performance obligations | ~$664bn |
| Capital expenditures | $28.5bn |
| Free cash flow | ($5.4bn) |
| Equity raised through at-the-market sales | $19.91bn |
Sources: Oracle Announces Q1 Results Driven by Triple Digit Growth in Cloud Infrastructure Revenues; Analysts maintain Oracle optimism despite project risks; Microsoft reportedly reduces older Oracle computing lease; Eisman discusses OpenAI and Oracle downside scenario
AAPLApple
On-device AI on Apple silicon
Runs Apple Intelligence features on its own chips in iPhones, iPads and Macs, with heavier requests handled in its Private Cloud Compute servers. Its AI exposure is mostly through device demand rather than cloud services.
What to watch: Apple was one of six names on Dan Ives' November 2 AI list. Track whether AI features change iPhone upgrade rates.
TSLATesla
Autonomy software and robotics
Trains driver-assistance and autonomy software on data from its vehicle fleet and is developing the Optimus humanoid robot. Most revenue still comes from vehicles and energy storage.
What to watch: Tesla was on Dan Ives' November 2 list. Its AI value depends on autonomy and robotics milestones that are not yet reflected in reported revenue.
BABAAlibaba Group (ADR)
Alibaba Cloud and Qwen models
Operates Alibaba Cloud, China's largest cloud provider, and develops the Qwen family of open-weight AI models.
What to watch: US export controls on advanced chips and China regulatory policy shape its access to compute. Track cloud segment growth and AI-related revenue disclosures.
Nos. 50–64, 15 companies
Neoclouds and data center operators
Specialist AI clouds and data center developers sit between chip suppliers and the AI labs and hyperscalers that rent capacity. They borrow heavily to buy GPUs or build powered buildings, then lease capacity under multi-year contracts. Several started as bitcoin miners and are converting their power sites. Digital Realty and Equinix, the large data center REITs, follow a slower, landlord model.
Reported earnings in this group are often dominated by noncash items such as warrant remeasurement or bitcoin gains, so cash flow, debt and contract quality are the more useful measures. Benzinga’s coverage in November ranged from a JPMorgan credit analyst seeing clearer funding to an investor warning that most neocloud providers could fail.
CoreWeave: from revenue to net loss
Q3 2026, quarter ended September 30
Capital purchases far exceed operating cash flow
Latest quarter; US$ billions
CRWVCoreWeave
GPU cloud for AI labs
Rents NVIDIA GPU capacity to AI labs and large technology companies under multi-year contracts. It is the largest listed specialist AI cloud and a bellwether for the group.
What to watch: Operating income of $207m covered only 0.24x of net interest expense ($846m). Operating cash flow minus cash capital purchases was ($7.47bn). JPMorgan's credit analyst saw clearer funding visibility; short seller Jim Chanos questioned returns on capital. Both views were reported by Benzinga on November 11.
Q3 2026, quarter ended September 30, 2026
| Revenue | $3.66bn (up ~168% YoY) |
| Adjusted EBITDA | $2.26bn |
| GAAP net loss | ($709m) |
| Revenue backlog | ~$132.5bn |
| Active / contracted power | >1,700 MW / >4,600 MW |
| 2026 capex guidance | $37−39bn |
November 11, 2026, late-morning snapshot: $60.04, up 23.20% intraday. Historical, not a current quote.
Sources: CoreWeave third-quarter company earnings release; Analyst relief after CoreWeave third-quarter results; CoreWeave backlog grows as Chanos questions capital returns; CoreWeave results trigger widespread AI stock rally
NBISNebius Group
AI cloud in Europe and the US
Builds and operates AI cloud capacity in Europe and the United States, with Microsoft among its customers.
What to watch: Shares fell about 15.86% on November 12 after Nebius said 2026 revenue would land near the low end of its range and some New Jersey capacity for Microsoft slipped to the second quarter of 2027. Quarterly financing inflows of $7.46bn funded the build-out. Nebius was on Shay Boloor's rebound list.
Q3 2026, quarter ended September 30, 2026
| Revenue | $980.8m (up ~571% YoY) |
| Adjusted EBITDA | $465.8m |
| Net loss, continuing operations | ($37.5m) |
| Operating cash flow, Q3 / nine months | ($273m) / $4.23bn |
| Cash purchases of PP&E and intangibles | $7.3bn |
| 2027 revenue guidance | $12−13bn |
November 11, 2026, late-morning snapshot: $155.88, up 16.32% intraday. Historical, not a current quote.
Sources: Nebius Reports Third Quarter 2026 Financial Results — financial results PDF; Nebius lowers outlook toward existing range bottom; Nebius third-quarter company earnings release; Strategist selects AI stocks following election volatility; CoreWeave results trigger widespread AI stock rally
IRENIREN
AI cloud built on bitcoin-mining sites
Converted bitcoin-mining sites into AI cloud capacity and now earns most of its revenue renting GPUs, with Microsoft among its customers.
What to watch: The 86% AI cloud segment margin excludes depreciation and site-level costs. The annualized revenue target moved from year-end into January and possibly February 2027, and the wider plan still requires about $6bn of additional financing. Shares rose 7.45% on November 11.
Q1 FY2027, quarter ended September 30, 2026
| Revenue | $228m |
| AI cloud revenue | $200m (up ~182% from prior quarter) |
| AI cloud revenue backlog | ~$20.3bn |
| Balance-sheet debt including finance leases | $10.21bn |
| Remaining FY2027 capex (management) | ~$15bn |
| Annualized revenue target, early 2027 | >$4bn |
Sources: IREN fiscal first-quarter company earnings release; IREN reports higher AI cloud revenue; Commentator supports IREN AI infrastructure economics; IREN faces renewed selling pressure
APLDApplied Digital
AI data center developer and landlord
Develops and leases large AI data center campuses in North Dakota, led by its Polaris Forge sites.
What to watch: Benzinga's earnings summary used the adjusted revenue figure while citing growth tied to GAAP revenue; the two differ by about $41m. Cash after capital purchases was ($2.01bn) for the quarter. Shares rose 9.11% on November 11.
Q1 FY2027, quarter ended August 31, 2026
| GAAP revenue | $341.9m (up ~322% YoY) |
| Adjusted revenue (excludes ChronoScale) | $300.4m |
| Net loss, continuing operations | ($168.0m) |
| Polaris Forge 1 ready-for-service capacity | 250 MW |
| Total debt | ~$6.4bn |
Sources: Applied Digital fiscal first-quarter company earnings release; Applied Digital fiscal first-quarter earnings; AI infrastructure shares rally after CoreWeave earnings
GLXYGalaxy Digital
Helios data center campus plus digital assets
Combines a digital-asset trading and investment business with the Helios data center campus in Texas, which leases capacity to CoreWeave.
What to watch: Most adjusted gross profit came from Treasury and Corporate investment gains ($418.9m), not data centers, so consolidated earnings should not be read as AI earnings. Lease income depends heavily on CoreWeave. Shares rose 15.31% on November 11.
Q3 2026, quarter ended September 30, 2026
| Data Centers segment revenue | $89.0m |
| Data Centers adjusted EBITDA | $68.7m |
| Delivered critical IT load | 133 MW |
| Helios II capacity approved, not yet leased | 830 MW |
| Notes issued to finance Helios I Phase II | $3.5bn |
Sources: Galaxy Announces Third Quarter 2026 Financial Results; Galaxy data-center outlook supports shares; Analysts assess Galaxy data-center expansion; AI infrastructure shares rally after CoreWeave earnings
WULFTeraWulf
Data center leasing to AI tenants
Develops and leases data center infrastructure at its Lake Mariner campus in New York and new sites, without owning the GPUs inside.
What to watch: Net income of $709.9m was driven by a $728.4m noncash gain on warrants and derivatives, not by operations. Benzinga reported Google credit support for financing tied to the Anthropic leases. Not owning GPUs reduces direct exposure to chip obsolescence.
Q3 2026, quarter ended September 30, 2026
| Revenue | $76.2m |
| HPC lease revenue | ~$63m |
| Operating loss | ($88.2m) |
| Anthropic lease initial contract revenue | ~$19bn over 20 years |
| Lake Mariner capacity, operating / under construction | 102 MW / 336 MW |
Sources: TeraWulf Reports Third Quarter 2026 Results; TeraWulf outlook draws attention amid sector volatility; TeraWulf third-quarter earnings discussion; TeraWulf shares follow AI infrastructure rally
CORZCore Scientific
Colocation capacity for AI tenants
Leases high-density colocation capacity to AI cloud tenants while running a smaller bitcoin-mining operation.
What to watch: Power-cost pass-through made up about 26.7% of colocation revenue, so not all colocation revenue is high-margin rent. Reported net income is dominated by noncash warrant effects.
Q3 2026, quarter ended September 30, 2026
| Revenue | ~$232.9m |
| Colocation revenue | $215.4m |
| Billing critical IT capacity | 485 MW |
| Net income (includes warrant remeasurement) | $1.18bn |
| Capex including land and rights | ~$985.1m |
Sources: Core Scientific Announces Third Quarter 2026 Results; Crypto miners expanding into AI face credit concerns
CIFRCipher Mining
Mining sites converted to HPC leases
A bitcoin miner converting its Texas power sites into data centers leased to large technology and AI customers under long-term contracts.
What to watch: Track lease commencement dates, tenant credit support and the financing of construction.
HUTHut 8
Power-dense sites for AI and mining
An energy and digital infrastructure company that develops power-dense sites for AI and high-performance computing alongside bitcoin mining.
What to watch: Track signed AI tenants, construction financing and the share of revenue still tied to bitcoin.
RIOTRiot Platforms
Powered land leased to AI tenants
A bitcoin miner that is leasing its Texas power capacity to AI data center tenants, including AMD and a new Corsicana anchor lease.
What to watch: Most current revenue is still bitcoin mining and engineering; the Corsicana lease economics are future management estimates. Benzinga's October coverage flagged credit risk as miners turn into data center developers.
Q3 2026, quarter ended September 30, 2026
| Revenue | ~$181.4m |
| Data center revenue | ~$18.4m |
| Corsicana lease contract value | ~$28bn over 15 years |
| Corsicana critical IT capacity under lease | 910 MW |
| Estimated Corsicana capital requirement | ~$5.5bn |
Sources: Riot Platforms Reports Third Quarter 2026 Financial Results and Strategic Highlights; Crypto miners expanding into AI face credit concerns
MARAMARA Holdings
Bitcoin miner developing power sites
A large bitcoin miner holding about 34,000 BTC that is developing power and data center capacity that could serve AI tenants.
What to watch: Net income reflected ~$885.3m of fair-value gains on bitcoin. After quarter end MARA sold 13,597 BTC and repaid $750m of bitcoin-backed loans. AI exposure is prospective rather than current.
Q3 2026, quarter ended September 30, 2026
| Revenue | $164.2m (down ~35% YoY) |
| Net income (includes digital-asset gains) | $632.1m |
| Bitcoin holdings including receivables | 34,012 BTC |
| Energized power capacity | ~1,900 MW |
Sources: MARA Q3 2026 Shareholder Letter; Crypto miners expanding into AI face credit concerns
SHAZSharonAI Holdings
Early-stage AI cloud, Asia-Pacific
An early-stage AI cloud provider planning large NVIDIA GPU deployments in Australia, New Zealand and the Asia-Pacific region.
What to watch: About ~$423.8m of the quarterly loss was noncash, mainly a convertible-note fair-value charge. The deployment plan is far larger than the current revenue base, so execution and financing carry most of the risk. Shares rose 14.49% on November 11.
Q2 2026, quarter ended June 30, 2026 (latest verified)
| Revenue | $1.93m |
| Net loss (mostly noncash) | ($430.4m) |
| NVIDIA compute collaboration | ~$4.9bn over 6 years |
| GPU-backed debt facility | $356m at 9.95% before fees |
| Planned GPU deployment by mid-2027 | >68,000 GPUs |
Sources: SharonAI second-quarter company earnings release; SharonAI announces financing for Nvidia GPU deployments; SharonAI partnership news offsets weaker earnings; Sharon AI Enters Into GPU-Backed Debt Facility, Expanding Funding Flexibility for AI Factory Deployments; AI infrastructure shares rally after CoreWeave earnings
DOCNDigitalOcean
Developer cloud adding GPU capacity
A cloud provider for developers and smaller companies that has added GPU capacity and inference services.
What to watch: DigitalOcean was on Shay Boloor's November 5 rebound list. Track AI revenue growth and the capital needed to add GPUs.
Sources: Strategist selects AI stocks following election volatility
EQIXEquinix
Colocation and interconnection REIT
A global data center REIT focused on colocation and interconnection, building larger hyperscale campuses through its xScale joint ventures.
What to watch: Track interconnection growth, xScale leasing and power availability in key metros.
DLRDigital Realty
Hyperscale and colocation data center REIT
A data center REIT that leases both large hyperscale blocks and smaller colocation and interconnection space.
What to watch: Much of the record leasing will not start paying rent until 2027 or 2028. Track commencements, funding needs and power delivery in markets such as Northern Virginia.
Q3 2026, quarter ended September 30, 2026
| Revenue | $1.9bn (up 21% YoY) |
| Leasing signed (annualized rent) | $855m ($627m at Digital Realty's share) |
| Signed-not-commenced backlog | $2.5bn ($1.8bn at share) |
| Core FFO per share | $2.10 |
Sources: Digital Realty Q3 2026 results release; Earnings Whispers: Digital Realty Q3 call transcript
Nos. 65–79, 15 companies
Enterprise software and AI applications
Software companies earn AI revenue by charging for agents, copilots and platforms built on top of models. Results vary widely. Palantir grew revenue 96% with a 46.9% GAAP operating margin, while C3.ai’s revenue fell 25.5%. Acquisitions complicate several comparisons: SoundHound, BigBear.ai and Salesforce all include acquired revenue.
AI is also a competitive threat in this layer. Benzinga tied ServiceNow’s November weakness to concern about Anthropic’s workplace tools, and Palantir fell after reporting strong results because of its valuation. The test is whether customers pay more, renew and expand at attractive margins.
Revenue growth across AI software companies
Year-over-year total revenue growth, latest reported quarter
PLTRPalantir Technologies
AIP platform for enterprises and government
Sells data integration and AI platforms (Foundry, Gotham and AIP) to US government agencies and a fast-growing base of commercial customers.
What to watch: Shares fell after the report as Benzinga highlighted the premium valuation and total contract value growth slowing to 6% from 49%. Stock compensation equaled about 13.8% of revenue. Palantir was on Dan Ives' November 2 list.
Q3 2026, quarter ended September 30, 2026
| Revenue | $2.31bn (up 96% YoY) |
| US commercial revenue | ~$984m (up 148% YoY) |
| GAAP operating margin | 46.9% |
| Adjusted free cash flow | $1.22bn |
| Net dollar retention | 165% |
| 2026 revenue guidance | $8.53−8.53bn |
Sources: Palantir third-quarter investor update; Palantir raises outlook after third-quarter earnings beat; Palantir shares decline despite strong results; Ives names technology stocks after sector selloff
NOWServiceNow
Workflow automation and AI agents
Sells a workflow platform for IT, HR and customer service and monetizes AI through premium AI-enabled subscription tiers and agents.
What to watch: Company-defined free cash flow adds back $74m of acquisition cash costs; without it, operating cash flow minus capex was $748m. Shares fell about 15.25% after hours on the report, and Benzinga tied November weakness to concern about Anthropic's workplace tools.
Q3 2026, quarter ended September 30, 2026
| Revenue | $4.11bn (up 20.5% YoY) |
| Subscription revenue | $3.99bn (up 21% YoY) |
| Current remaining performance obligations | ~$13.7bn |
| Free cash flow (company definition) | $822m |
| Year-end 2026 AI annual contract value target | $1.7bn |
Sources: ServiceNow Reports Third Quarter 2026 Financial Results; ServiceNow shares decline after mixed quarterly results; Anthropic products intensify concerns about ServiceNow competition
CRMSalesforce
CRM with Agentforce AI agents
Sells customer-relationship software and is pushing Agentforce, its AI agent product, and Data 360 across its customer base. Results include the acquired Informatica business.
What to watch: GAAP EPS of $4.29 included a $2.43-per-share gain from strategic investments, and non-GAAP EPS still carried a $2.53 gain effect. The ARR definition now covers more products, so prior-period comparisons need checking.
Q2 FY2027, quarter ended July 31, 2026
| Revenue | $11.35bn (up 11% YoY) |
| Informatica contribution to revenue | $456m |
| Agentforce ARR | >$1.5bn (up >240% YoY) |
| Agentforce and Data 360 ARR | ~$3.9bn |
| FY2027 revenue guidance | $46.1−46.4bn |
Sources: Salesforce Delivers Record Second Quarter Fiscal 2027 Results; Salesforce AI growth faces investor skepticism; Analyst links Agentforce adoption to Salesforce renewals
SNOWSnowflake
Data cloud and AI agents on enterprise data
Runs a cloud data platform where enterprises store and query data, and sells AI agents and model access that run on that governed data.
What to watch: Product revenue growth accelerated for a third straight quarter, which management attributed partly to AI products. GAAP operating loss was $263m, against non-GAAP operating income of $237m.
Q2 FY2027, quarter ended July 31, 2026
| Product revenue | $1.49bn (up 37% YoY) |
| Net revenue retention | 126% |
| Remaining performance obligations | $9.0bn (up 30% YoY) |
| FY2027 product revenue guidance | $6.07bn (up 36%) |
Sources: Snowflake Q2 FY2027 results release; Pulse 2.0: Snowflake guidance raised
CRWDCrowdStrike
AI-assisted endpoint and cloud security
Sells the Falcon cybersecurity platform, which uses AI models for threat detection and automates security operations.
What to watch: CrowdStrike posted a GAAP operating loss of (~$33.2m) against non-GAAP operating income of ~$371.6m. Its results are cybersecurity revenue, not separately measured AI revenue. CrowdStrike was on Dan Ives' list.
Q2 FY2027, quarter ended July 31, 2026
| Revenue | $1.47bn (up 26% YoY) |
| Annual recurring revenue | ~$5.8bn (up 25% YoY) |
| Net new ARR | $332.8m |
| Free cash flow | $377.4m |
| FY2027 revenue guidance | $5.99−6.01bn |
Sources: CrowdStrike Reports Second Quarter Fiscal Year 2027 Financial Results; Ives names technology stocks after sector selloff
PANWPalo Alto Networks
Network, cloud and AI security
Sells network firewalls, cloud security and security-operations software, including tools to secure AI applications and agents.
What to watch: Palo Alto appears on Benzinga's evergreen AI stock guide. Track next-generation security ARR and platform consolidation deals.
IBMIBM
watsonx, Red Hat and AI consulting
Sells hybrid cloud software (Red Hat), the watsonx AI platform, mainframes and consulting services that implement AI for large enterprises.
What to watch: IBM reports generative AI as a share of consulting backlog rather than a dollar total. Full-year guidance calls for 4% to 5% constant-currency revenue growth.
Q3 2026, quarter ended September 30, 2026
| Revenue | $17.1bn (up 5% YoY) |
| Software revenue | $7.8bn (up 8% YoY) |
| Free cash flow | $3.0bn |
| Consulting backlog with generative AI embedded | 35% |
Sources: IBM Q3 2026 results release; IBM Q3 2026 results (full text); FourWeekMBA: IBM generative AI share of consulting backlog
ADBEAdobe
Firefly generative models in Creative Cloud
Builds Firefly generative image and video models into Creative Cloud and adds AI assistants to Acrobat and its marketing software.
What to watch: Track AI-influenced recurring revenue and competition from standalone image and video generators.
DDOGDatadog
Observability for AI workloads
Sells monitoring and observability software, including tools to track the cost and performance of AI models and applications. AI-native companies are a growing customer group.
What to watch: Track revenue concentration among large AI-native customers.
NETCloudflare
Edge network and AI inference
Runs a global edge network for security and performance and offers AI inference on GPUs deployed across that network.
What to watch: Track large-customer growth and adoption of its developer and AI products.
APPAppLovin
AI-driven advertising engine
Runs a mobile and e-commerce advertising platform whose results depend on its AI recommendation engine, Axon.
What to watch: Track e-commerce advertiser adoption and any regulatory scrutiny of its data practices.
TEMTempus AI
AI in diagnostics and clinical data
Sells genomic testing and licenses de-identified clinical data, using AI tools to support diagnosis and drug development.
What to watch: Track testing volumes, data licensing revenue and progress toward sustained profitability.
SOUNSoundHound AI
Voice AI and customer-service agents
Sells voice AI for automakers, restaurants and devices and, after acquiring LivePerson, customer-service software.
What to watch: About ~$14m of quarterly revenue (22.4%) came from LivePerson, which closed September 4. Management targets sustained positive adjusted EBITDA in the second half of 2027. Cantor Fitzgerald cut its price target to $10.00 from $15.00.
Q3 2026, quarter ended September 30, 2026
| Revenue | $62.4m (up 48.5% YoY) |
| Revenue growth excluding LivePerson | ~15% |
| GAAP net loss | ($46.4m) |
| Adjusted EBITDA | ($20.7m) |
| 2027 revenue guidance | $350−400m |
Sources: SoundHound third-quarter company results and profitability outlook; Analysts assess SoundHound earnings and outlook
BBAIBigBear.ai
Decision intelligence for defense
Sells decision-intelligence and generative AI software, including Ask Sage, mainly to US defense and security agencies.
What to watch: The net loss included a $76.7m noncash goodwill impairment, while quarterly operating cash outflow was ($9.55m). Growth includes the Ask Sage acquisition and is not an organic figure.
Q3 2026, quarter ended September 30, 2026
| Revenue | $43.6m (up 31% YoY) |
| GAAP net loss | ($91.9m) |
| Adjusted EBITDA | ($9.08m) |
| Backlog | ~$330m |
| 2026 revenue guidance | $150−165m |
Sources: BigBear.ai third-quarter company earnings release; BigBear.ai reports growth in generative AI platform revenue
AIC3.ai
Enterprise AI applications
Sells packaged enterprise AI applications and a development platform to industrial, energy and government customers.
What to watch: Stock compensation of $59.2m was about 113% of quarterly revenue. Management cut the workforce by about 40% in a restructuring, and full-year guidance still includes a non-GAAP operating loss of $123m to $155m.
Q1 FY2027, quarter ended July 31, 2026
| Revenue | $52.4m (down 25.5% YoY) |
| Subscription revenue | $49.2m |
| GAAP operating loss | ($98.3m) |
| Free cash flow | ~$2.10m |
| FY2027 revenue guidance | $210−240m |
Sources: C3.ai fiscal first-quarter company earnings release; C3.ai reports progress in first-quarter turnaround; C3.ai fiscal first-quarter earnings discussion
Nos. 80–85, 6 companies
Power generation
Data centers need firm power, and the grid connection is often the longest lead-time item in a project. Owners of existing nuclear and gas plants can sign long-term supply agreements with technology companies. Fuel-cell and small-reactor developers offer on-site alternatives, on longer and less certain timelines.
Power announcements use megawatts to describe very different things: new generation, existing output under contract, or financial agreements that do not involve delivering a specific plant’s output. Constellation’s agreements show why the figures should not be added together.
Constellation’s announced agreements are different kinds of megawatts
Megawatts by agreement
CEGConstellation Energy
Nuclear power under hyperscaler contracts
The largest US nuclear operator, selling power under long-term agreements with Amazon, Google and other buyers. It acquired Calpine's gas fleet in January 2026.
What to watch: The 690 MW Amazon agreement includes existing output, and the 2,700 MW Google agreement is a financial load-following contract, so the headline megawatts should not be added together as new generation. The CEO argued that underused existing generation can serve more data center demand.
Q3 2026, quarter ended September 30, 2026
| Revenue | $9.55bn |
| GAAP net income | $1.83bn |
| Nuclear capacity factor | 97.2% |
| Google-supported nuclear uprates | ~890 MW |
| 2026 adjusted operating EPS guidance | $12.50−$12.80 |
Sources: Constellation Reports Third Quarter 2026 Results; Constellation discusses unused electricity capacity for AI; Constellation outlines its power supply business model
VSTVistra
Texas nuclear and gas generation
Owns nuclear, gas and coal plants, mainly in Texas and the PJM market, and runs a large retail power business. It is signing power agreements with data center developers.
What to watch: GAAP net income of $1.14bn included a $559m unrealized hedging gain. A 20-year agreement with New Era supports a proposed Texas data center that was still seeking tenants when Benzinga reported it.
Q3 2026, quarter ended September 30, 2026
| Revenue | $6.35bn |
| Ongoing-operations adjusted EBITDA | $2.38bn |
| 2027 adjusted EBITDA guidance | $7.7−8.5bn |
| Gas capacity acquired with Cogentrix | ~5,500 MW |
| Expected 2027 generation already hedged | ~98% |
Sources: Vistra Reports Third Quarter 2026 Results; Vistra third-quarter earnings discussion; Vistra signs long-term electricity agreement for AI development
TLNTalen Energy
PJM generation with data center deals
An independent power producer in the PJM market that supplies Amazon's data center campus next to its Susquehanna nuclear plant.
What to watch: Growth includes acquired gas plants. GAAP net income fell to $138m on derivative swings. Talen expanded its buyback to $3bn and is marketing additional baseload capacity and powered land to large-load customers.
Q3 2026, quarter ended September 30, 2026
| Revenue | ~$1.33bn (up 63% YoY) |
| Adjusted EBITDA | $669m |
| Adjusted free cash flow | $433m |
| 2027 adjusted EBITDA guidance | $2.50−2.85bn |
Sources: Talen Q3 2026 results release; Earnings Whispers: Talen Q3 2026
NRGNRG Energy
Generation and retail power in Texas
An integrated power company with generation and a large retail electricity business, exposed to rising demand in Texas and the PJM region.
What to watch: Track signed data center supply agreements and new generation projects in Texas.
BEBloom Energy
On-site fuel-cell power
Makes solid-oxide fuel-cell systems that provide on-site power for data centers that cannot wait for a grid connection.
What to watch: Track data center orders, margins on new installations and financing partners.
November 11, 2026, late-morning snapshot: $213.99, up 15.40% intraday. Historical, not a current quote.
Sources: CoreWeave results trigger widespread AI stock rally
OKLOOklo
Pre-commercial small nuclear reactors
A pre-commercial developer of small fast-fission reactors (the Aurora powerhouse) aimed at data centers and industrial users, with fuel and isotope businesses on the side.
What to watch: The first plant's startup window widened from 2028 to 2028–2029, and PJM withdrew a Virginia interconnection application. Funding relies on at-the-market share sales. The Meta-backed Ohio campus agreement is not a binding commitment to build a reactor.
Nine months ended September 30, 2026
| Net loss, nine months | ($123.3m) |
| Cash, equivalents and marketable securities | $3.1bn |
| First Aurora startup window | 2028 to 2029 |
| 2026 capex guidance | $400−500m |
Sources: Earnings Whispers: Oklo Q3 2026 review; MarketBeat: Oklo Q3 call highlights
Nos. 86–94, 9 companies
Electrical, cooling and grid equipment
AI racks draw far more power and produce far more heat than conventional servers, which lifts demand for transformers, switchgear, backup generation, turbines and liquid cooling. Orders have grown faster than revenue: Vertiv’s organic orders more than doubled, and GE Vernova’s gas turbine backlog and reservations reached 122 gigawatts.
Strong demand did not protect these stocks from the November 10 selloff. Reported growth also includes acquisitions, so organic growth is the cleaner comparison.
Reported and organic revenue growth
Q3 2026, year over year
VRTVertiv
Power and liquid cooling for data centers
Supplies power distribution, backup power and thermal management, including liquid cooling, for AI data centers.
What to watch: The CFO told Benzinga customers were accepting higher prices, with manufacturing capacity and available power the main constraints. Vertiv was on Shay Boloor's rebound list. Its shares still fell in the broad November 10 supplier selloff.
Q3 2026, quarter ended September 30, 2026
| Revenue | $4.31bn (up 61% YoY; 55% organic) |
| Adjusted operating margin | 25.2% |
| Organic order growth | >100% |
| Adjusted free cash flow | $652m |
| 2026 revenue guidance | $14.45−14.85bn |
Sources: Vertiv third-quarter company results and higher outlook; Vertiv discusses pricing and customer demand; Strategist selects AI stocks following election volatility; AI infrastructure suppliers face broad selling pressure
ETNEaton
Electrical distribution and power management
Makes switchgear, power distribution and power-management equipment for data centers, utilities and industry, alongside aerospace and vehicle businesses.
What to watch: Acquisitions added eight percentage points to growth. Shares reversed an initial rally after the report despite an EPS beat and higher guidance, as analysts weighed policy and permitting concerns.
Q3 2026, quarter ended September 30, 2026
| Revenue | $8.95bn (up 28% YoY; 19% organic) |
| Segment operating margin | 25.3% |
| Electrical Americas organic orders, rolling 12 months | up 39% |
| Electrical backlog growth | up 46% |
| Free cash flow | ~$1bn |
Sources: Eaton Reports Record Third Quarter 2026 Results, with Strong Organic Growth, Accelerating Record Orders and Backlog; Raises Organic Growth Guidance; Analysts assess Eaton after earnings
GEVGE Vernova
Gas turbines and grid equipment
Makes gas turbines, grid equipment and wind turbines. Data center demand has filled its gas turbine order book for years ahead.
What to watch: Slot reservations are not as firm as signed equipment orders. GE Vernova also announced an agreement to acquire Trench Group, a grid equipment maker.
Q3 2026, quarter ended September 30, 2026
| Revenue | ~$12.6bn (up 27% YoY; 18% organic) |
| Orders | ~$29bn (up 96% organic) |
| Backlog / remaining performance obligations | ~$197bn |
| Gas equipment backlog plus slot reservations | 122 GW |
| 2026 free cash flow guidance | $16−17bn |
Sources: GE Vernova reports strong third quarter 2026 financial performance, raises 2026 guidance, and increases share repurchase authorization; GE Vernova Releases Third Quarter 2026 Financial Results & Announces Agreement to Acquire Trench Group
NVTnVent Electric
Enclosures and liquid cooling
Makes electrical enclosures, connection products and liquid-cooling systems used in data centers and utility infrastructure.
What to watch: Track data center liquid-cooling orders and capacity additions.
MODModine Manufacturing
Data center cooling systems
Makes thermal management products, with data center cooling (chillers and air handlers) now its main growth business.
What to watch: Track data center segment growth and margin as new capacity comes online.
CATCaterpillar
Engines and turbines for on-site power
Supplies reciprocating generator sets and Solar gas turbines used for backup and on-site prime power at data centers.
What to watch: Caterpillar was among the suppliers in Benzinga's November 10 selloff report. Track power-generation sales within its energy and transportation segment.
Sources: AI infrastructure suppliers face broad selling pressure
AMSCAmerican Superconductor
Grid and power-quality equipment
Sells grid power-quality and voltage-control equipment and wind turbine electrical systems.
What to watch: Growth includes acquisitions. AMSC was one of seven names in Tim Melvin's November 3 list; the author noted none had a confirmed Anthropic contract.
Q2 FY2026, quarter ended September 30, 2026
| Revenue | $94.0m (up 42.8% YoY) |
| Grid revenue | $76.7m |
| Net income | $3.00m |
| Q3 FY2026 revenue guidance | >$80m |
Sources: AMSC fiscal second quarter 2026 results; Contributor identifies smaller AI infrastructure companies
HMDPFHammond Power Solutions
Dry-type transformers
Makes dry-type transformers and power magnetics used in data centers and industrial facilities. HMDPF is the US over-the-counter symbol; the primary listing is HPS.A in Toronto.
What to watch: Growth includes acquisitions, and backlog dipped from the prior quarter. Figures are in Canadian dollars and are not converted.
Q3 2026, quarter ended September 26, 2026 (Canadian dollars)
| Revenue | C$446.3m (up 104.4% YoY) |
| Adjusted EBITDA margin | 18.8% |
| Net income | C$27.7m |
| Power Magnetics backlog, YoY / quarter-on-quarter | up 61.1% / down 3.8% |
Sources: Hammond Power Solutions third quarter 2026 results; Contributor identifies smaller AI infrastructure companies
PPIHPerma-Pipe International
Pre-insulated piping incl. cooling
Makes pre-insulated piping systems used in district energy, oil and gas, and cooling infrastructure.
What to watch: Total sales are not AI revenue; data center cooling is one end market among several.
Q2 FY2026, quarter ended July 31, 2026
| Revenue | $59.6m (up 24.4% YoY) |
| Gross margin | 29.2% |
| Backlog | $142.3m |
| Receivable impairment provision | $3.90m |
Sources: Perma-Pipe fiscal second quarter 2026 results; Contributor identifies smaller AI infrastructure companies
Nos. 95–100, 6 companies
Construction and engineering
Contractors build the substations and transmission lines that connect data centers to the grid, and the electrical and mechanical systems inside them. Backlog is the main indicator, but definitions range from signed contracts to work that has been awarded but not yet signed.
How much construction backlog is firm
Share of reported backlog, September 30, 2026
PWRQuanta Services
Grid and power construction
Builds and maintains electric transmission, distribution and generation infrastructure, including connections for large data center loads.
What to watch: Free cash flow of $1.20bn deducts net capex after asset-sale and insurance proceeds. Acquisitions and diversified end markets mean revenue growth is not all AI-related.
Q3 2026, quarter ended September 30, 2026
| Revenue | ~$12bn |
| Net income attributable to common stock | $694.9m |
| Total backlog | ~$63.7bn |
| Remaining performance obligations | ~$41.8bn |
| 2026 revenue guidance | $41.3−41.6bn |
EMEEMCOR Group
Electrical and mechanical contracting
Provides electrical and mechanical construction, with data centers a large part of its network and communications work.
What to watch: Track remaining performance obligations in network and communications projects.
FIXComfort Systems USA
Mechanical and modular construction
Provides mechanical, electrical and modular construction for technology facilities, including data centers.
What to watch: Track the technology share of backlog and modular capacity.
AMRCAmeresco
Energy infrastructure projects
Develops energy efficiency and on-site energy projects for governments and companies, including data center energy infrastructure.
What to watch: Most backlog ($4.56bn) was awarded but not yet signed. Operating cash flow was ($8.85m) for the quarter.
Q3 2026, quarter ended September 30, 2026
| Revenue | $580.3m (up 10.3% YoY) |
| Total project backlog | $7.15bn |
| Contracted share of backlog | 36.2% |
| Data center energy infrastructure awards | $200m |
| 2026 revenue guidance | $2.13−2.15bn |
Sources: Ameresco third quarter 2026 results; Contributor identifies smaller AI infrastructure companies
MECMayville Engineering
Fabrication for data center equipment
A contract metal fabricator with a fast-growing data center and critical power end market.
What to watch: Data center and critical power was about 21.8% of revenue. Guidance still calls for negative free cash flow this year.
Q3 2026, quarter ended September 30, 2026
| Revenue | $170.4m (up 18.1% YoY) |
| Datacenter and Critical Power revenue | $37.2m (up 64.9% YoY) |
| Net leverage | 2.9x |
| 2026 free cash flow guidance | ($16m) to ($6m) |
Sources: Mayville Engineering third quarter 2026 results; Contributor identifies smaller AI infrastructure companies
MTRXMatrix Service
Energy and utility construction
Builds energy, utility and power infrastructure, including storage terminals and power delivery projects.
What to watch: Awards below revenue for one quarter do not prove a structural slowdown, but the cash outflow is worth monitoring.
Q1 FY2027, quarter ended September 30, 2026
| Revenue | $219.4m (up 3.5% YoY) |
| Backlog | $872.6m |
| Awards to revenue | 0.63x |
| Operating cash flow | ($37.0m) |
| Cash / debt | ~$182.4m / none |
Sources: Matrix Service fiscal first quarter 2027 results; Contributor identifies smaller AI infrastructure companies
Analyst and strategist picks
Several AI stock lists circulated in early November. They come from different authors with different methods, so repeated mentions do not measure merit. Use them to find research candidates, then check each argument and its date.
| Source and date | Names | Basis |
|---|---|---|
| Dan Ives, November 2 | NVDA, MSFT, PLTR, CRWD, AAPL, TSLA | Selections across six AI subsectors after the tech selloff |
| Shay Boloor, November 5 | AMD, VRT, CRDO, DOCN, NBIS | Post-election rebound thesis separating construction delays from compute demand |
| Cantor Fitzgerald, November 9 | NVDA, AVGO, AMD, MU, SNDK, ASML, AMAT, LRCX, KLAC | Semiconductor valuation and cycle thesis, partly based on 2028 earnings estimates |
| Tim Melvin, November 3 | AMSC, HMDPF, AMRC, MEC, PPIH, MTRX, TSSI | Small-cap infrastructure suppliers; the author noted none had a confirmed Anthropic contract |
| Benzinga evergreen guide | MSFT, NVDA, META, NOW, PANW, TSM, CLS | General idea list; its body text retained references from earlier in the year |
A November 2 partner article on Benzinga paired a microcap with Meta, Salesforce and ServiceNow and carried a disclosure that its distributor had been paid to produce it. Paid content of that kind was not used to select companies for this guide.
The case for and against
The case for
Demand is in reported revenue. NVIDIA, Broadcom, TSMC, Micron and Sandisk are reporting sharply higher sales and profits, not projections. The demand is visible at every layer, from equipment orders to cloud revenue.
Contracts extend visibility. Microsoft reported about $677bn of commercial remaining performance obligations, Oracle about $664bn and Google Cloud a backlog of about $561bn. Customer prepayments are funding part of the build-out.
Scarce power favors existing assets. Bernstein favors operating data centers with secured power, and portfolio managers quoted by Benzinga argued that limited new supply could improve pricing for established cloud providers.
Monetization is broadening. Custom chips, networking, memory and software are taking a growing share of spending, so returns are no longer tied to a single GPU supplier.
Multiples have come down. Semiconductors traded at about 13.5 times forward earnings in early November, below the S&P 500.
The case against
Spending is running ahead of cash. Alphabet, Meta and Oracle spent more than their operating cash flow in the latest quarter, Amazon’s trailing free cash flow was negative, and hyperscaler bond issuance has climbed.
Financing is interlinked. Suppliers invest in customers that buy their products, lenders can hold overlapping claims on the same GPUs, and neoclouds carry large debts. One forecast cited by Benzinga projects that more than 80% of neocloud providers will cease to operate independently by 2030.
Depreciation will rise. One forecast holds that up to 40% of 2026 AI capital spending will not be in service until 2027 to 2029. As it enters service, depreciation will weigh on earnings, and the useful life of GPUs is still uncertain, as the Microsoft and Oracle lease report illustrated.
Customer concentration. Backlog at several companies in this guide depends on a small number of AI labs and hyperscalers. Steve Eisman outlined how trouble at OpenAI could reach Oracle and the wider economy.
Good results are not enough. Broadcom, Palantir and ServiceNow all fell after reporting growth. When expectations are high, a strong quarter can still disappoint.
Seven checks before buying an AI stock
The same issues come up across all 11 segments. Working through them for any single company separates the businesses with durable AI earnings from those carried by the theme.
- Separate AI revenue that is already recognized from targets, annualized run rates, backlog and awarded but unsigned work.
- Look at what remains after depreciation, interest and stock-based compensation, not only adjusted EBITDA.
- Find out how much construction and equipment spending still needs financing, on what terms and with how much dilution.
- Identify the customers behind revenue and backlog, and whether they can fund their commitments.
- Confirm that power, permits and delivery milestones are secured for the sites that matter.
- Check how much growth is organic and whether metrics are defined the same way from period to period.
- Work out what growth and margins the current share price already assumes.
AI ETFs and concentration
Exchange-traded funds offer a simpler way to hold the theme, but the largest AI and semiconductor funds overlap heavily. NVIDIA alone made up about 20.04% of the VanEck Semiconductor ETF in mid-October, according to Benzinga. Owning several AI funds therefore does not diversify much across the spending cycle. A January interview on the AI ETF trade came from an executive at a competing fund provider, which is relevant context for its recommendations.
Glossary
- Accelerator
- A chip designed to run AI calculations in parallel. GPUs from NVIDIA and AMD are the best-known type; custom accelerators (often called XPUs or ASICs) are designed for a single customer.
- HBM
- High-bandwidth memory: stacks of DRAM packaged beside an accelerator to feed it data quickly.
- Hyperscaler
- One of the largest cloud operators, such as Microsoft, Alphabet, Amazon, Meta and Oracle.
- Neocloud
- A specialist cloud provider that rents GPU capacity for AI, such as CoreWeave or Nebius.
- Backlog / RPO
- Contracted revenue not yet recognized. Remaining performance obligations follow an accounting standard; backlog definitions vary by company and may include awarded work that is not signed.
- ARR
- Annualized recurring revenue: a run rate based on current contracts or usage, not recognized revenue.
- Adjusted EBITDA
- Earnings before interest, taxes, depreciation and amortization, with other company-chosen exclusions. It leaves out the cost of equipment wearing out and the cost of debt.
- Free cash flow
- Operating cash flow minus capital spending. Companies define it differently, so check what is added back or deducted.
- Capex
- Capital expenditure: spending on long-lived assets such as data centers, servers and chip-making tools. Some companies include finance leases.
- Organic growth
- Revenue growth excluding acquisitions and currency effects.
- Critical IT load (MW)
- The power available to run servers in a data center, excluding cooling and other overhead.
- Power purchase agreement
- A long-term contract to buy electricity. Some deliver a specific plant’s output; others are financial hedges.
- Uprate
- An upgrade that increases the output of an existing power plant.
- Forward P/E
- Share price divided by expected earnings over the next 12 months. It depends on analysts’ forecasts.
- ADR
- American depositary receipt: a US-listed certificate representing shares of a foreign company, such as TSMC, ASML, SK hynix or Alibaba.
- Stock-based compensation
- Pay in shares or options. It does not use cash but dilutes existing shareholders.
Method and sources
How the 100 were chosen
The list starts with the 55 companies that featured in Benzinga’s AI coverage through November 12, 2026, with financial figures checked against each company’s own release or filing. It adds 11 companies named in analyst and strategist lists that Benzinga carried, and 34 widely followed companies needed to complete each layer of the value chain. Companies appear in chapter order, by segment, and the numbering does not rank them.
Coverage depth varies. 43 entries carry detailed figures, 17 carry key figures from their latest release, 8 carry the November 11 price snapshot and 32 are business profiles. A profile without figures means current-quarter numbers were not verified for this edition, not that the company is less important.
Reading the figures
Amounts are in US dollars unless marked: NT$ for Taiwan dollars, C$ for Canadian dollars and € for euros. Currencies are not converted. A tilde (~) marks an approximate figure as reported. Negative amounts appear in parentheses. Growth is year over year unless labeled otherwise. GAAP figures follow standard accounting rules; adjusted and non-GAAP figures follow each company’s own definitions, which differ. Guidance, management targets and analyst forecasts are labeled as such and are not results.
Figures should not be added across companies to estimate the size of the AI market. Supply-chain revenue overlaps: NVIDIA’s sales are part of Microsoft’s capex, which becomes Dell’s and Super Micro’s revenue, and so on.
Sources
- CoreWeave results trigger widespread AI stock rally Benzinga, Nov. 11, 2026
- AI infrastructure shares rally after CoreWeave earnings Benzinga, Nov. 11, 2026
- Analysts compare technology valuations with earlier AI enthusiasm Benzinga, Nov. 3, 2026
- AI infrastructure suppliers face broad selling pressure Benzinga, Nov. 10, 2026
- Gerstner flags potential data-center project risks Benzinga, Nov. 4, 2026
- Analyst argues AI selloff overstates election risks Benzinga, Nov. 6, 2026
- Local elections add uncertainty to data-center development Benzinga, Nov. 12, 2026
- Analysts weigh semiconductor buying opportunities after steep declines Benzinga, Nov. 9, 2026
- Survey highlights crowded chip positioning and customer debt Benzinga, Sept. 16, 2026
- Carlyle discusses private-credit exposure to AI financing Benzinga, Oct. 13, 2026
- Analysts assess AI infrastructure depreciation risks Benzinga, Oct. 25, 2026
- Nvidia fiscal second-quarter company earnings release Company release, Aug. 26, 2026
- AMD third-quarter company earnings release Company release, Nov. 3, 2026
- Broadcom fiscal third-quarter company earnings release Company release, Sept. 2, 2026
- Marvell Technology, Inc. Reports Second Quarter of Fiscal Year 2027 Financial Results Marvell Technology, Aug. 27, 2026
- Intel Q3 2026 results release Accessed Nov. 12, 2026
- Arm Q2 FYE27 results Accessed Nov. 12, 2026
- Munster outlines Nvidia platform growth thesis Benzinga, Oct. 21, 2026
- Broadcom growth meets higher investor expectations Benzinga, Sept. 2, 2026
- AMD discusses infrastructure readiness for future deployments Benzinga, Nov. 4, 2026
- Strategist selects AI stocks following election volatility Benzinga, Nov. 5, 2026
- Marvell projects growth in custom AI chips Benzinga, Oct. 7, 2026
- Marvell and Lumentum definitive transaction announcement Marvell SEC filing, Nov. 2, 2026
- Marvell and Lumentum transaction analysis Benzinga, Nov. 2, 2026
- Neoteo: Arm Q2 FY2027 figures and guidance Accessed Nov. 12, 2026
- Benzinga: Qualcomm Q4 highlights Accessed Nov. 12, 2026
- Securities.io: Qualcomm data center target Accessed Nov. 12, 2026
- Micron Technology, Inc. Reports Record Fiscal Fourth-Quarter and Full-Year 2026 Results Micron Technology, Sept. 30, 2026
- Sandisk fiscal Q1 2027 results release Accessed Nov. 12, 2026
- FourWeekMBA: Sandisk data center mix Accessed Nov. 12, 2026
- Micron benefits from improved AI infrastructure sentiment Benzinga, Nov. 11, 2026
- Kyunghyang Shinmun: SK hynix lists ADRs on Nasdaq Accessed Nov. 12, 2026
- New Straits Times: SK hynix ADR pricing Accessed Nov. 12, 2026
- MarketBeat: Sandisk Q1 call highlights Accessed Nov. 12, 2026
- 24/7 Wall St.: Sandisk results and stock split Accessed Nov. 12, 2026
- TSMC Reports Third Quarter EPS of NT$29.43 TSMC, Oct. 15, 2026
- ASML Q3 2026 results Accessed Nov. 12, 2026
- iConnect007: KLA fiscal Q1 2027 results Accessed Nov. 12, 2026
- Lam Research September 2026 quarter release (SEC) Accessed Nov. 12, 2026
- TSMC October consolidated revenue report Company release, Nov. 10, 2026
- TSMC shares respond to AI investment and revenue growth Benzinga, Nov. 11, 2026
- ASML Q3 2026 press release Accessed Nov. 12, 2026
- MarketBeat: Lam Research call highlights Accessed Nov. 12, 2026
- Securities.io: KLA fiscal Q1 detail Accessed Nov. 12, 2026
- Arista Networks, Inc. Reports Third Quarter 2026 Financial Results Arista Networks, Nov. 3, 2026
- Credo Technology Group Holding Ltd Reports First Quarter of Fiscal Year 2027 Financial Results Credo Technology, Sept. 1, 2026
- Astera Labs Q3 2026 release (SEC) Accessed Nov. 12, 2026
- Arista outlines timing of AI networking opportunities Benzinga, Nov. 4, 2026
- MarketBeat: Cisco Q4 FY2026 call highlights Accessed Nov. 12, 2026
- Pulse 2.0: Cisco AI infrastructure orders Accessed Nov. 12, 2026
- Earnings Whispers: Astera Labs results Accessed Nov. 12, 2026
- Dell Q2 FY2027 release Accessed Nov. 12, 2026
- StorageNewsletter: Dell fiscal 2Q27 Accessed Nov. 12, 2026
- Supermicro Q1 FY2027 release (SEC) Accessed Nov. 12, 2026
- Pulse 2.0: Dell outlook raised Accessed Nov. 12, 2026
- Securities.io: Supermicro outlook Accessed Nov. 12, 2026
- Celestica Q3 2026 release (SEC) Accessed Nov. 12, 2026
- Celestica Q3 2026 release and Q4 guidance Accessed Nov. 12, 2026
- Evertiq: Celestica 2027 outlook Accessed Nov. 12, 2026
- Earnings Whispers: Celestica Q3 review Accessed Nov. 12, 2026
- Benzinga evergreen guide to AI stocks Benzinga, updated Nov. 2026
- TSS third quarter 2026 results TSS SEC exhibit, Nov. 5, 2026
- Contributor identifies smaller AI infrastructure companies Benzinga, Nov. 3, 2026
- Microsoft official fiscal first-quarter earnings discussion Company release, Oct. 28, 2026
- Alphabet official third-quarter earnings discussion Company release, Oct. 28, 2026
- Meta third-quarter company earnings release Company release, Oct. 21, 2026
- Oracle Announces Q1 Results Driven by Triple Digit Growth in Cloud Infrastructure Revenues Oracle, Sept. 10, 2026
- CoreWeave third-quarter company earnings release CoreWeave / SEC exhibit, Nov. 10, 2026
- Microsoft Announces First Quarter Results Microsoft, Oct. 28, 2026
- Microsoft fiscal first-quarter earnings discussion Benzinga, Oct. 28, 2026
- Microsoft reviews computing contracts with neocloud providers Benzinga, Nov. 7, 2026
- Microsoft reportedly reduces older Oracle computing lease Benzinga, Nov. 6, 2026
- Alphabet third-quarter earnings discussion and transcript correction Benzinga, Oct. 29, 2026
- Analysts cut Alphabet targets while largely retaining bullish ratings Benzinga, Oct. 29, 2026
- Alphabet spending raises concerns about near-term margins Benzinga, Oct. 29, 2026
- Amazon third-quarter company earnings release Company release, Oct. 29, 2026
- Amazon third-quarter earnings discussion Benzinga, Oct. 29, 2026
- Commentators assess Amazon growth after earnings selloff Benzinga, Oct. 29, 2026
- Meta third-quarter earnings discussion Benzinga, Oct. 21, 2026
- Analysts maintain Oracle optimism despite project risks Benzinga, Nov. 10, 2026
- Eisman discusses OpenAI and Oracle downside scenario Benzinga, Nov. 10, 2026
- Ives names technology stocks after sector selloff Benzinga, Nov. 2, 2026
- Nebius Reports Third Quarter 2026 Financial Results — financial results PDF Nebius Group, Nov. 12, 2026
- IREN fiscal first-quarter company earnings release IREN investor relations, Nov. 5, 2026
- Applied Digital fiscal first-quarter company earnings release Applied Digital investor relations, Oct. 7, 2026
- Analyst relief after CoreWeave third-quarter results Benzinga, Nov. 11, 2026
- CoreWeave backlog grows as Chanos questions capital returns Benzinga, Nov. 11, 2026
- Nebius lowers outlook toward existing range bottom Benzinga, Nov. 12, 2026
- Nebius third-quarter company earnings release Nebius via Business Wire/Benzinga, Nov. 12, 2026
- IREN reports higher AI cloud revenue Benzinga, Nov. 5, 2026
- Commentator supports IREN AI infrastructure economics Benzinga, Nov. 6, 2026
- IREN faces renewed selling pressure Benzinga, Nov. 9, 2026
- Applied Digital fiscal first-quarter earnings Benzinga, Oct. 7, 2026
- Galaxy Announces Third Quarter 2026 Financial Results Galaxy Digital, Oct. 27, 2026
- Galaxy data-center outlook supports shares Benzinga, Oct. 27, 2026
- Analysts assess Galaxy data-center expansion Benzinga, Oct. 28, 2026
- TeraWulf Reports Third Quarter 2026 Results TeraWulf / SEC exhibit, Nov. 6, 2026
- TeraWulf outlook draws attention amid sector volatility Benzinga, Nov. 4, 2026
- TeraWulf third-quarter earnings discussion Benzinga, Nov. 6, 2026
- TeraWulf shares follow AI infrastructure rally Benzinga, Nov. 11, 2026
- Core Scientific Announces Third Quarter 2026 Results Core Scientific, Nov. 5, 2026
- Crypto miners expanding into AI face credit concerns Benzinga, Oct. 24, 2026
- Riot Platforms Reports Third Quarter 2026 Financial Results and Strategic Highlights Riot Platforms, Nov. 4, 2026
- MARA Q3 2026 Shareholder Letter MARA Holdings, Nov. 9, 2026
- SharonAI second-quarter company earnings release SharonAI investor relations, Aug. 6, 2026
- SharonAI announces financing for Nvidia GPU deployments Benzinga, Oct. 1, 2026
- SharonAI partnership news offsets weaker earnings Benzinga, Aug. 12, 2026
- Sharon AI Enters Into GPU-Backed Debt Facility, Expanding Funding Flexibility for AI Factory Deployments SharonAI / PRNewswire via Benzinga, Oct. 1, 2026
- Digital Realty Q3 2026 results release Accessed Nov. 12, 2026
- Earnings Whispers: Digital Realty Q3 call transcript Accessed Nov. 12, 2026
- Palantir third-quarter investor update Company release, Nov. 2, 2026
- SoundHound third-quarter company results and profitability outlook Company release, Nov. 5, 2026
- BigBear.ai third-quarter company earnings release Company release, Oct. 27, 2026
- C3.ai fiscal first-quarter company earnings release Company release, Sept. 2, 2026
- ServiceNow Reports Third Quarter 2026 Financial Results ServiceNow, Oct. 28, 2026
- Salesforce Delivers Record Second Quarter Fiscal 2027 Results Salesforce, Aug. 26, 2026
- CrowdStrike Reports Second Quarter Fiscal Year 2027 Financial Results CrowdStrike, Aug. 26, 2026
- Snowflake Q2 FY2027 results release Accessed Nov. 12, 2026
- IBM Q3 2026 results release Accessed Nov. 12, 2026
- Palantir raises outlook after third-quarter earnings beat Benzinga, Nov. 2, 2026
- Palantir shares decline despite strong results Benzinga, Nov. 3, 2026
- ServiceNow shares decline after mixed quarterly results Benzinga, Oct. 28, 2026
- Anthropic products intensify concerns about ServiceNow competition Benzinga, Nov. 10, 2026
- Salesforce AI growth faces investor skepticism Benzinga, Sept. 14, 2026
- Analyst links Agentforce adoption to Salesforce renewals Benzinga, Sept. 18, 2026
- Pulse 2.0: Snowflake guidance raised Accessed Nov. 12, 2026
- IBM Q3 2026 results (full text) Accessed Nov. 12, 2026
- FourWeekMBA: IBM generative AI share of consulting backlog Accessed Nov. 12, 2026
- Analysts assess SoundHound earnings and outlook Benzinga, Nov. 6, 2026
- BigBear.ai reports growth in generative AI platform revenue Benzinga, Oct. 27, 2026
- C3.ai reports progress in first-quarter turnaround Benzinga, Sept. 2, 2026
- C3.ai fiscal first-quarter earnings discussion Benzinga, Sept. 2, 2026
- Constellation Reports Third Quarter 2026 Results Constellation Energy, Nov. 9, 2026
- Constellation discusses unused electricity capacity for AI Benzinga, Nov. 10, 2026
- Constellation outlines its power supply business model Benzinga, Nov. 10, 2026
- Vistra Reports Third Quarter 2026 Results Vistra, Nov. 6, 2026
- Vistra third-quarter earnings discussion Benzinga, Nov. 6, 2026
- Vistra signs long-term electricity agreement for AI development Benzinga, Sept. 21, 2026
- Talen Q3 2026 results release Accessed Nov. 12, 2026
- Earnings Whispers: Talen Q3 2026 Accessed Nov. 12, 2026
- Earnings Whispers: Oklo Q3 2026 review Accessed Nov. 12, 2026
- MarketBeat: Oklo Q3 call highlights Accessed Nov. 12, 2026
- Vertiv third-quarter company results and higher outlook Company release, Oct. 28, 2026
- Eaton Reports Record Third Quarter 2026 Results, with Strong Organic Growth, Accelerating Record Orders and Backlog; Raises Organic Growth Guidance Eaton via SEC EDGAR, Nov. 3, 2026
- GE Vernova reports strong third quarter 2026 financial performance, raises 2026 guidance, and increases share repurchase authorization GE Vernova, Oct. 28, 2026
- Vertiv discusses pricing and customer demand Benzinga, Nov. 11, 2026
- Analysts assess Eaton after earnings Benzinga, Nov. 4, 2026
- GE Vernova Releases Third Quarter 2026 Financial Results & Announces Agreement to Acquire Trench Group GE Vernova, Oct. 28, 2026
- AMSC fiscal second quarter 2026 results AMSC, Nov. 4, 2026
- Hammond Power Solutions third quarter 2026 results Hammond Power Solutions via GlobeNewswire, Oct. 29, 2026
- Perma-Pipe fiscal second quarter 2026 results Perma-Pipe, Sept. 9, 2026
- Ameresco third quarter 2026 results Ameresco, Nov. 9, 2026
- QUANTA SERVICES REPORTS THIRD QUARTER 2026 RESULTS Quanta Services, Oct. 29, 2026
- Mayville Engineering third quarter 2026 results Mayville Engineering SEC exhibit, Nov. 3, 2026
- Matrix Service fiscal first quarter 2027 results Matrix Service SEC exhibit, Nov. 4, 2026
- Investors assess cloud pricing under capacity constraints Benzinga, Nov. 5, 2026
- Semiconductor ETF structures expose different AI concentration risks Benzinga, Oct. 15, 2026
- Interview examines changing risks in AI-themed funds Benzinga, Jan. 11, 2026
This guide is for information only. It is not investment advice or a recommendation to buy or sell any security, and it does not consider any reader’s financial situation. Figures come from company filings and releases, Benzinga coverage and other cited reporting available on November 12, 2026, and may have changed since. Analyst opinions and price targets belong to the analysts quoted. Verify figures with the original source before relying on them.
Cp vs. Cpk: Formulas, Examples and How to Interpret Process Capability
DFMEA vs. PFMEA: Differences, Examples and When to Use Each
Top Lead Generation Companies for Engineering Businesses (2026)
Engineering Design Essentials: From Power Systems to Prototyping
The Complexity of Modern Engineering Design Designing engineering systems is as much about avoiding mistakes as it is about innovation. Every decision — whether it’s choosing a material, configuring a control system, or running a thermal simulation — has consequences...
How to Build a Future-Proof Engineering Career: Skills, Salaries, Licensing, ROI, and Career Transitions
Why Career Strategy Matters for Engineers Engineering has always been a field where technical expertise meets real-world impact. Yet the modern engineering workforce faces challenges that extend beyond design equations and CAD models. Job security, career advancement,...